
Is Kornit Digital Ltd. (KRNT) a good stock to buy?
Nothing we have tested argues against it, and one check argues for it.
What each rating means, in numbers
Business quality — Strong. Passes 7 of the 9 health checks we can measure — things like making a profit, turning it into cash, and not piling on debt. Across 131,000 company-quarters the weakest scorers went on to fail at 5.4% against 1.4% for the strongest, in every era and all twelve sectors.
How wild is the price? — Average. The share price swings about 39% in a typical year, which puts it in the middling. Out of every 100 companies that swung like this, about 1.5 went bankrupt within the year. Across the three periods we tested that ran from 0.2% to 3.0%.
What "tested" means here, and why there is no score out of 100
Tested means the read was measured against what actually happened afterwards, on a history that keeps the companies that were later delisted, using only figures that had been filed on the day they are used. Survival was ranked on companies that really did fail. What an owner keeps was tested across the universe from 2011 to 2025.
The full record of everything we have tested is on the research pages.
Which benchmark. Over the period we tested, the median listed company returned +5.8% a year while the S&P 500 returned about +13.9% — the index is weighted by size and was carried by a handful of enormous winners. So "beats the index" and "beats the other companies you could have bought" are different questions. Where a read says it picks better companies, it means the second one. None of these gets you an index fund's return, and we would rather say that than imply otherwise.
The quality read is the strongest thing we have tested: 131,000 company-quarters across 5,300 companies, where the weakest scorers went on to fail at 5.4% against 1.4% for the strongest, holding in every era and all twelve sectors. It still says less likely to break, not likely to beat the market — every band in that study lost to the index at the median, because the median listed company does.
Each read is shown on its own rather than merged into a single score, so you can see which part is strong and which is weak instead of taking an average on trust.
▾ What goes into the smart-money reading
Contributions (weight × component score) sum to the total. This near-term score now includes fundamental health (leverage, FCF trend). It excludes the Altman Z score, whose retained-earnings input this filer does not report separately. See the Financial Health section for the full balance-sheet read.
Chance the S&P 500 falls 10% or more in the next three months.
Counted from every day since 2006. Says nothing about KRNT — see the board for how it is measured.
📍 Where to start on this page, and what to look at first
How to read KRNT (pre-profit growth)
This company is reinvesting instead of generating profit, so a standard DCF cannot price it. The useful question is whether the growth the market is paying for is achievable — and whether the company can fund itself until then.
-
1
Reverse-DCF — the growth the price demands ↓
It shows exactly how fast the business must grow to justify today's price. Compare that to what comparable companies have actually achieved.
-
2
Cash runway ↓
Can it reach profitability before it has to raise money and dilute shareholders?
-
3
Interactive calculator ↓
Set your own growth + margin assumptions and see what the business would be worth if you are right.
Our DCF for KRNT lands well below today's price. For a non-cyclical that usually means the market is pricing in growth far beyond recent cash flows (or there's a data quirk), so we don't headline a single fair-value number.
What to use instead: The Reverse-DCF shows exactly how much growth the price demands — decide whether that's realistic. Pair it with peer multiples.
This note is only about the single DCF fair-value number — KRNT's full financial statements, health scores, and written analysis are all below.
Who owns KRNT, and how it moves
From the SEC's own filings: every fund manager over $100M reports its holdings each quarter, and every officer and director reports theirs. Each point is what was public at the time.
⚠ We found only 2 genuine same-industry (Special Industry Machinery) comparables — fewer than the 4 we require for a reliable median. The 8 names in the table below therefore include 6 broader Industrials names marked fallback, whose business models and margins differ — which is why any median below is computed over that wider set, not over true comparables. So we do not derive a peer-implied share value here. Read the multiples as rough context only.
How does KRNT stack up against its closest peers?
Ideally we compare KRNT only to same-industry peers, but too few exist in our universe right now, so the basket below mixes in broader-sector names. Treat the multiples as rough context, not a valuation. For a leveraged business, EV/EBIT and FCF yield (both in the table) are usually more reliable than EV/Sales, because revenue multiples ignore differences in margins and debt.
▾ What's "EV / Sales" in plain English?
EV (Enterprise Value) = market cap + total debt − cash. It's "what you'd pay to buy the entire company outright" — you pay the market cap to shareholders and take over their debt, but you keep their cash. EV is fairer than market cap alone because it includes the debt the new owner inherits.
EV / Sales = EV ÷ annual revenue. So "2.5×" means investors pay $2.50 of enterprise value per $1 of yearly sales. Higher = market is paying more per dollar of sales (usually because they expect future growth or fat margins).
p25 / median / p75 are the 25th, 50th (middle), and 75th percentile of the peers' multiples. Half the peers fall between p25 and p75. The median (p50) is the typical peer — that's the benchmark we compare to.
| EV / SalesEV / Sales — For every $1 of yearly revenue, this is how many dollars investors pay to own the whole business (including debt). Why it matters: Works for pre-profit growth companies where P/E and FCF don't apply. The most apples-to-apples cross-company multiple because it ignores accounting choices. Reference: 1–3x for mature companies · 4–10x for software/SaaS · 10–20x for hypergrowth · >20x is rare and demanding Full explanation → |
1.3x / 2.5x / 5.4x |
| EV / Gross ProfitEV / Gross Profit — Enterprise value divided by gross profit — the multiple paid for what each dollar of sales contributes after direct costs. Why it matters: More refined than EV/Sales for high-margin businesses (software, marketplaces) where gross margin is the real economic engine. Reference: 8–15x for SaaS · 15–25x for hypergrowth software · >30x demanding Full explanation → |
2.2x / 4.9x / 6.3x |
| EV / EBITEV / EBITDA — Enterprise value divided by earnings before interest, tax, depreciation, and amortization. Why it matters: A classic "what would a private buyer pay" multiple — used in M&A. Strips out tax and capital-structure noise. Reference: 8–12x for mature businesses · 15–25x for growth · Below 5x often signals distress Full explanation → |
12.0x / 17.6x / 29.2x |
Bold middle number = median peer. Half the peers trade above it, half below. Computed over 8 peers (broad — see caveat); implausible multiples excluded.
⚠️ Important caveat: peer multiples only work if the peers are genuinely comparable. Always check the peer list below — if the auto-picker grabbed micro-caps or unrelated businesses, the comparison is noise. A medical-device giant priced against tiny biotech startups won't produce a useful signal.
▾ View peer list (8)
| Ticker | Company | Industry | Mcap | EV/Sales | EV/GP | EV/EBIT | FCF Yield |
|---|---|---|---|---|---|---|---|
| CRCT | Cricut, Inc. | Special Industry Machinery | $871M | 1.2x | 2.2x | 9.1x | 18.3% |
| AZTA | Azenta, Inc. | Special Industry Machinery | $1.7B | 2.9x | 6.3x | — | 1.0% |
| VELO | Velo3D, Inc. | Special Industry Machinery ·fallback | $716M | 16.2x | — | — | 0.0% |
| ERII | Energy Recovery, Inc. | Special Industry Machinery ·fallback | $421M | 3.1x | 4.8x | 17.6x | 2.6% |
| HTZ | HERTZ GLOBAL HOLDINGS, INC | Auto Rental & Leasing ·fallback | $549M | 2.1x | — | — | 261.5% |
| VTOL | Bristow Group Inc. | Air Courier ·fallback | $1.2B | 1.3x | — | 12.0x | 3.2% |
| WLDN | Willdan Group, Inc. | Engineering Services ·fallback | $1.2B | 1.9x | 5.0x | 29.2x | 4.8% |
| WLFC | WILLIS LEASE FINANCE CORP | Machinery, Equipment & Sup ·fallback | $1.2B | 5.4x | — | 37.8x | 16.7% |
Quality & solvency checks
Cheap stocks can be cheap for a reason. These screens warn when a low valuation comes paired with structural fragility.
What these health ratings mean, in numbers
Business quality — Strong. Passes 7 of the 9 health checks we can measure — making a profit, turning it into cash, not piling on debt, not issuing shares. Across 131,000 company-quarters the weakest scorers went on to fail at 5.4% within a year against 1.4% for the strongest, and that held in every era and all twelve sectors. It says "less likely to break", not "likely to beat the market".
Why it matters: Cheap-looking stocks (low P/E or P/B) often have low Z-scores because the market knows the company is dying. Z-score warns you before you fall into a value trap.
Reference: > 3.0 = safe zone · 1.81–3.0 = grey zone · < 1.81 = distress zone
Full explanation →
We can't produce a trustworthy Altman Z here: retained earnings weren't separately reported in our data, so a core input would have to be fabricated. Rather than show a categorical "distress" verdict from an invented number, we mark it unavailable. Judge financial health from the leverage, cash position, and the measurable Piotroski checks instead.
Why it matters: High score = fundamentals improving. Low score = deteriorating. Especially powerful for filtering cheap stocks: cheap + high F-score historically outperforms; cheap + low F-score is often a value trap.
Reference: 7–9 = strong · 4–6 = mediocre · 0–3 = weak
Full explanation →
▾ The checks — what passed, what didn't (and what we couldn't measure)
-
✗ Positive net incomeNet income -$13.5M in FY2025.Why this matters: Does the company actually earn a profit? Sustained losses eventually force it to raise money — diluting you — or take on debt.
-
✓ Positive operating cash flowOperating cash flow $24.6M (was $48.7M the prior year).
-
✓ Cash flow backs up reported profitOperating cash flow $24.6M vs net income -$13.5M.
-
✓ Return on assets improvingReturn on assets -1.8% vs -2.1% a year ago.
-
✓ Debt load (vs assets)The filing reports no interest-bearing debt in either year (total assets $770.5M).
-
✓ Short-term liquidity (current ratio)Current ratio 14.18x vs 13.88x a year ago.
-
✓ Share count (dilution)Share count declined 4.7% (47.5M → 45.2M year-over-year), so the no-dilution check passed. (One-year change; the multi-year buyback pace can differ.)
-
✗ Pricing power (gross margin)Gross margin 44.3% vs 45.0% a year ago.Why this matters: Rising gross margin means stronger pricing power or lower input costs — a sign of competitive strength. Falling margin signals pressure.
-
✓ Sales per asset (asset turnover)Asset turnover 0.27x vs 0.26x a year ago.
Missing data is never counted as a pass or a fail — it's shown as n/a and excluded from the denominator. Each check compares the company against its own prior year.
What if you assume different inputs?
Here's where we land — and what happens if you change the assumptions. Drag the sliders to set your own Discount RateDiscount Rate — The annual return you demand for taking single-stock risk instead of buying a safe Treasury or index fund.
Why it matters: Higher discount rate = stricter valuation (a stock has to produce more cash to be worth holding). Lower = more generous.
Reference: 8–12% is standard · 9–10% matches S&P 500 historical return · Below 7% is illogical for single-stock risk
Full explanation → (the annual return you demand for single-stock risk) and terminal growth; the value updates live so you can see whether the stock looks cheaper or richer. The discount rate starts at 10.0%, the figure our model used for KRNT. Open Advanced to also change beta, growth and the rate path.
Note: no headline intrinsic value is published for this stock (the valuation is held for a data-quality reason — see the notes above). The calculator below is a what-if tool: the values it produces are your assumptions played out, not our estimate.
A full intrinsic value isn't shown for KRNT because the valuation is currently held for a data-quality reason (see the guardrail notes above). The reverse-DCF reading still works — it needs only the price and cash flow — but we won't publish a forward value until the underlying data passes our checks.
—
⚙ Advanced — tinker with every input (beta, growth, rate path, margin → full intrinsic value)
A standard discounted cash flowDCF — Discounted Cash Flow — sums up all future cash a business will produce, adjusted for the fact that future dollars are worth less than dollars today.
Why it matters: It is the most fundamentally honest valuation method when applicable — but only works for companies with predictable, positive cash flow.
Reference: Best for: mature, profitable businesses. Fails for: pre-profit growth, banks, REITs.
Full explanation → (DCF) valuation is not meaningful for Kornit Digital Ltd. due to its negative free cash flowFree Cash Flow (FCF) — Operating cash flow minus capital spending: cash left after a company covers operating costs, taxes and interest and reinvests in the business — but BEFORE repaying debt principal or paying dividends. The cash actually available to investors.
Why it matters: A company can show big profits on paper while burning through cash. FCF is what actually fills the bank account.
Reference: Healthy mature businesses convert 8–15% of revenue into FCF · Growth companies often negative
Full explanation → after stock compensation of -$18.6 million and negative net income of -$13.5 million in the latest fiscal year. Valuing this company would require projecting a clear path to sustained profitability and positive free cash flow. Investors are likely betting on future revenue growth and potential margin expansion. The biggest risk to our assumptions is the continued revenue DECLINING at -10.3% per year over the last four years, indicating a shrinking core business.
As of 16 days ago
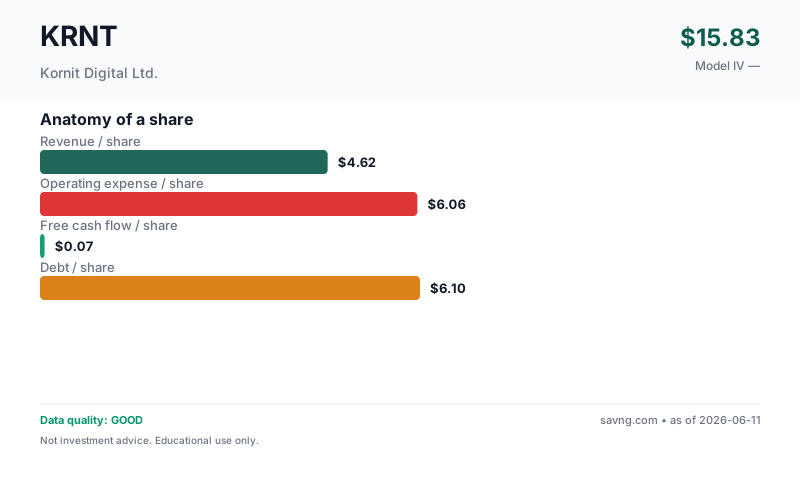
Anatomy of a share
What you're buying per share. Bars are at the same scale so you can see the relative size of revenue, costs, cash flow, and debt — not just read them in a table.
What's free cash flow / what do these mean?
Revenue per share — how much the business earns from customers, divided by the number of shares outstanding. Top of the income statement.
Earnings per share — profit left after operating costs, interest, and taxes, per share. Two versions appear on this page and are not interchangeable: GAAP diluted EPS uses the company's weighted-average diluted share count during the reporting period (this is the "earnings" in "price-to-earnings"); net income per current share divides annual net income by today's share count. They differ whenever the share count has changed.
Owner-earnings free cash flow per share — the cash the business produces for shareholders. Savng's owner-earnings FCF subtracts capital expenditures and stock-based compensation from operating cash flow (SBC is a real dilution cost even though it's non-cash). This is deliberately more conservative than "standard" FCF, which subtracts only capital expenditures — so our figure is lower than the headline FCF you'll see elsewhere. FCF funds dividends, buybacks, debt repayment, and acquisitions; a company can report positive earnings yet negative FCF.
Debt per share — total interest-bearing borrowings divided by shares. High debt-per-share next to thin FCF-per-share is a fragility signal.
What you actually need to decide
Every stock price is a disagreement. Here's the single thing that must go right for the bulls, the single thing that breaks the thesis, and the concrete signposts to watch so you can update your view as real results arrive.
- Quarterly revenue growth rates
- Gross margin trends
- New product adoption rates
The trend, in plain numbers (FY2024 → FY2025, latest reported)
Straight from the financial statements — no model, no opinion. For a small or unprofitable company, the direction of these numbers usually tells you more than any single valuation.
- Revenue grew +2% to $208.2M.
- Still unprofitable at -$13.5M — loss narrowing.
- Free cash flow is negative at -$18.6M — the cash burn widened vs last year.
- Gross margin shrank to 44% (-1 pts).
Management & Leadership
Ronen Samuel serves as the Chief Executive Officer, with Assaf Zipori as the Chief Financial Officer. Other key executives include Daniel Gazit as Chief Product Officer and Yaaqov Mann as Chief Technology Officer.
Chief Executive Officer
Chief Financial Officer
Chief Product Officer
Chief Technology Officer
What They Make
Kornit Digital Ltd. develops, manufactures, and markets digital printing solutions for the textile industry. Customers, primarily textile manufacturers and garment decorators, pay for these systems and related consumables.
End Markets
Revenue Drivers
Why Is It Priced Like This?
Why Customers Pay
What we use instead: earnings (P/E, EV/EBIT), book value (P/B) — computed from the figures this company does report, shown in the sections below. Those numbers are unaffected by the missing cash-flow data.
The market is likely pricing Kornit Digital based on expectations for future revenue growth and a potential return to consistent profitability, rather than current cash flows, given its negative net income and free cash flowFree Cash Flow (FCF) — Operating cash flow minus capital spending: cash left after a company covers operating costs, taxes and interest and reinvests in the business — but BEFORE repaying debt principal or paying dividends. The cash actually available to investors.
Why it matters: A company can show big profits on paper while burning through cash. FCF is what actually fills the bank account.
Reference: Healthy mature businesses convert 8–15% of revenue into FCF · Growth companies often negative
Full explanation →. The market may be assigning value to the company's innovation pipeline in digital textile printing technology, which is not in the model, or to the potential for significant market share capture in a growing niche, which is also not in the model. The current valuation reflects a bet on the company's ability to reverse its revenue DECLINING trend (-10.3%/yr over 4yr) and improve its COMPRESSING gross margin (47.2% → 44.3%).
Business Model & Valuation
How They Make Money
The company funds itself through its operating cash flow, which was positive at $24.6 million in the latest fiscal year, and has reduced its long-term debt from $9 million to $0 million.
Growth / Revenue DCF
Negative free cash flow: revenue/margin growth model used - standard FCF DCF is unreliable for companies still scaling.
Show advanced inputs
| Revenue Growth | 2.0% |
What this model does NOT do: this is a consolidated owner-earnings FCF model. Standalone segment assumptions: none. It does not project its revenue segments independently; their combined effect is embedded in the historical revenue and cash-flow trend the model extrapolates. The calculator above can only approximate a segment's impact through the single consolidated growth rate — it cannot model any one line separately. For a true segment-level view, build a separate model from the company's segment disclosures.
Maturity & Competitive Position
Moat Signals
Revenue has been DECLINING at -10.3% per year over the last four years, from $322 million to $208.2 million.
Geography & Markets
Kornit Digital Ltd. is headquartered in Israel and operates globally, serving customers across various international markets, though specific geographic revenue mix percentages are not available from current data sources.
Geographic Risks
Market Signals
These are timing signals, not value signals — they describe the stock's recent price behavior, not what the business is worth. Use them for the "the thesis looks good, but is now the moment?" question. Each tile below explains what it's saying.
Why it matters: Short-term contrarian indicator. Extreme readings often precede mean reversion, though not always.
Reference: 30–70 normal · >70 overbought · <30 oversold
Full explanation → (14)38.2NeutralMomentum is balanced — neither overbought nor oversold.
Why it matters: When the fast line crosses above the slow line, short-term momentum is turning up; below, turning down. A timing cue, not a value signal.
Reference: Line above signal = bullish momentum · below = bearish
Full explanation →BearishLine below signalThe fast trend is below the slow trend — short-term momentum is currently downward.
Technicals describe price, not the business. A great company can have a "bearish" tape (a buying chance) and a weak one a "bullish" tape (a trap). Pair these with the valuation and health sections above.
QUALITY
Data Quality & Risk Flags (8 notes — click to expand/collapse)
Guardrail Notes (7)
- FCF negative: revenue/margin growth model projects future cash flows from revenue trajectory.
- Terminal growth set to 1.6% — the lowest of the applicable caps (binding: 80% of near-term growth (2%)). We use one effective terminal rate everywhere on the page.
- Price is far above the model output - market may be pricing optionality, narrative catalysts, or margin expansion beyond what trailing cash flows support.
- Illiquidity discount 7% applied (small/micro-cap — harder to exit, demand a margin).
- Extreme valuation: the price is far above the model output for a non-cyclical — likely dominated by a data issue. The model value is suppressed.
- VALUATION HELD (EXTREME_MODEL_GAP): per-share values suppressed due to the model output failed plausibility checks.
- Extreme valuation gap (P/IV withheld — see the note above): result may be dominated by model assumptions, share count issues, or sector-specific dynamics. Treat as low confidence.
FINANCIALS
Financial Statements (5-year tables — click to expand)
From Kornit Digital Ltd.'s SEC filings (EDGAR).
Income (5yr)
| Year | Revenue | Net Income | EPS |
|---|---|---|---|
| 2025 | 208.2M | -13.5M | $-0.30 |
| 2024 | 203.8M | -16.8M | $-0.35 |
| 2023 | 219.8M | -64.4M | $-1.31 |
| 2022 | 271.5M | -79.1M | $-1.59 |
| 2021 | 322.0M | 15.5M | $0.32 |
Cash Flow (5yr)
| Year | Operating CF | CapEx | − SBC | Free Cash Flow |
|---|---|---|---|---|
| 2025 | 24.6M | 21.3M | 21.9M | -18.6M |
| 2024 | 48.7M | 15.1M | 21.8M | 11.8M |
| 2023 | -34.7M | 7.0M | 22.6M | -64.3M |
| 2022 | -99.3M | 18.0M | 22.6M | -140.0M |
| 2021 | 53.6M | 14.5M | 15.1M | 24.0M |
How we define FCF: operating cash flow − capital expenditure − stock-based compensation (owner-earnings basis — SBC is a real cost to shareholders even though it's non-cash). Latest year: 24.6M − 21.3M − 21.9M (stock-based comp) = -18.6M. This is the same owner-earnings FCF definition the valuation model uses, though the DCF's starting value is a projected from revenue × terminal margin, not this single year.
Balance Sheet
| Total Assets | 770.5M |
| Total Liabilities | 57.9M |
| Equity | 712.6M |
Similar companies worth a look
Same sector and industry, similar fundamentals shape. Verify everything yourself — this list is computed mechanically and does not reflect our judgment about whether any of these are a good investment.
The questions people ask about KRNT
Is Kornit Digital Ltd. (KRNT) a good stock to buy?
We do not publish a single fair value for Kornit Digital Ltd., because one number would not be reliable for this business (the page explains why). Judge it on what today's price assumes, its financial-health checks and what insiders are doing, all shown here from SEC filings. This is educational research from SEC filings, not investment advice.
Is Kornit Digital Ltd. (KRNT) overvalued?
A single fair-value number is not reliable for Kornit Digital Ltd., so we do not call it overvalued or undervalued. The page shows what growth today's price assumes and how the company's finances look instead. This is educational research from SEC filings, not investment advice.
What growth is priced into KRNT?
Working backwards from today's price, the market is counting on roughly 31.7% a year growth in KRNT's cash flow over the next decade. Compare that with the company's actual record on this page.
Where do these numbers come from?
From Kornit Digital Ltd.'s own SEC filings (10-K and 10-Q), Form 4 insider filings and daily market prices. Every figure on the page links to how it was calculated, and the model's weak spots are listed next to its results.