
Amplify Commodity Trust (BDRY) Stock Analysis
Amplify Commodity Trust
▾ What's in the 58/100 risk score? (higher = riskier)
Contributions (weight × component score) sum to the total. This near-term score now includes fundamental health (leverage, FCF trend, DCF applicability). See the Financial Health section for the full balance-sheet read.
We cannot answer this one. None of the reads we have tested could be computed for this company, so anything below is description, not evidence.
What "tested" means here, and why there is no score out of 100
Tested means the read was measured against what actually happened afterwards, on a history that keeps the companies that were later delisted, using only figures that had been filed on the day they are used. Survival was ranked on companies that really did fail. What an owner keeps was tested across the universe from 2011 to 2025. A valuation finding appears only when the cheap fifth of that business type beat the index — 156 of the 206 combinations we tried did not.
Not tested means we compute it and find it useful, but we have never measured whether it predicts anything. Our own model valuation is in that category. It is shown, and it does not decide the verdict.
There is no single score because we have not tested one. Combining five reads into one number implies somebody checked that the combination works, and nobody has. When that test exists, a number can appear here.
📍 Where to start on this page, and what to look at first
How to read BDRY (bank / insurer)
Banks and insurers are valued on what they earn on their capital, not on free cash flow — a normal DCF misleads here.
-
1
Bank / Insurance lens (P/TBV + ROE) ↓
Price-to-tangible-book versus return-on-equity is how analysts actually judge a bank cheap or rich.
-
2
Financial-health screens ↓
Watch the trend in profitability and asset quality, not the (not-applicable) bankruptcy score.
Is now a good time to buy BDRY?
Macro: Neutral / mid-cycleBDRY trades at $15.72 vs an estimated intrinsic value of $4.03 — a +290.2% premium to model IV.
Not investment advice. The model can be wrong. Verify the assumptions in the sections below and consider consulting a licensed advisor for significant decisions.
What return would BDRY pay as a bond?
Not measurable here. Banks and insurers have no owner-earnings coupon in the operating sense — their deposits and float are the business. The bank lens (book value + return on equity) is the comparable read. See the cross-company ranking →
Football field: where does the price sit?
Different valuation methods produce different fair-value ranges depending on assumptions. Plotting them together lets you see at a glance whether the current price is reasonable across approaches, or only one specific lens.
Industry multiples sourced from: broad market average (sector unknown). See the Peer Basket section below for the peer comparison and its limited-comparables caveat.
How does BDRY stack up against its closest peers?
We take the 8 same-industry companies most similar to BDRY (similar size) and check what investors are paying for each dollar of their revenue (or profits). If BDRY is much more expensive on the same yardstick, that's a red flag — unless you have a specific reason it deserves a premium. For a leveraged business, EV/EBIT and FCF yield (both in the table) are usually more reliable than EV/Sales, because revenue multiples ignore differences in margins and debt.
▾ What's "EV / Sales" in plain English?
EV (Enterprise Value) = market cap + total debt − cash. It's "what you'd pay to buy the entire company outright" — you pay the market cap to shareholders and take over their debt, but you keep their cash. EV is fairer than market cap alone because it includes the debt the new owner inherits.
EV / Sales = EV ÷ annual revenue. So "2.5×" means investors pay $2.50 of enterprise value per $1 of yearly sales. Higher = market is paying more per dollar of sales (usually because they expect future growth or fat margins).
p25 / median / p75 are the 25th, 50th (middle), and 75th percentile of the peers' multiples. Half the peers fall between p25 and p75. The median (p50) is the typical peer — that's the benchmark we compare to.
Bold middle number = median peer. Half the peers trade above it, half below. Computed over 8 same-industry peers; implausible multiples excluded.
⚠️ Important caveat: peer multiples only work if the peers are genuinely comparable. Always check the peer list below — if the auto-picker grabbed micro-caps or unrelated businesses, the comparison is noise. A medical-device giant priced against tiny biotech startups won't produce a useful signal.
▾ View peer list (8)
| Ticker | Company | Industry | Mcap | EV/EBIT | FCF Yield |
|---|---|---|---|---|---|
| UDN | INVESCO DB US DOLLAR INDEX BEARISH | Investment Banking | $144M | 35.0x | 6.2% |
| TOXR | 21Shares XRP ETF | Investment Banking | $143M | — | — |
| PALL | abrdn Palladium ETF Trust | Investment Banking | $149M | — | 265.3% |
| UGA | United States Gasoline Fund, LP | Investment Banking | $121M | — | — |
| WEAT | Teucrium Commodity Trust | Investment Banking | $182M | — | — |
| TAGS | Teucrium Commodity Trust | Investment Banking | $192M | — | — |
| FXA | Invesco CurrencyShares Australian | Investment Banking | $107M | — | 1.0% |
| SOYB | Teucrium Commodity Trust | Investment Banking | $196M | — | — |
How to value a bank (not a DCF question)
A bank's economic engine is the shareholder equity on its balance sheet — what the accountants say is left over after all loans, deposits, and liabilities are netted out. The bank earns a percentage on that equity each year (its ROE). So the two questions are: (1) what are you paying per dollar of equity (Price / Book)? and (2) how much is that equity actually earning (ROE)? Free cash flow doesn't work here — banks lend out their cash for a living.
Why it matters: For banks and insurers, book value is the regulatory capital they earn returns on. P/B is the cleanest comparison: 1.0× means buying the bank at the same price the accountants say it's worth.
Reference: 0.8–1.2× = fair for average bank · 1.5–2.0× = solid franchise · >2.5× = premium · <0.8× = potentially cheap or distress
Full explanation →
Premium to book — market expects above-average returns on this equity.
Why it matters: For a bank, ROE is the engine. A bank earning 15% on equity will compound book value at ~15%/year if it retains earnings. Combined with P/B, ROE tells you whether a premium price is supported by returns.
Reference: <8% = weak · 10–12% = solid · 15%+ = excellent · >20% sustained = exceptional franchise
Full explanation →
Why it matters: For banks especially, ROA isolates underwriting and operating efficiency from leverage. Two banks with identical ROE may have very different ROAs — one earning it cleanly, one earning it on borrowed money.
Reference: <0.8% = weak · 1.0–1.2% = solid · >1.5% = excellent (very rare for big banks)
Full explanation →
ROA differs from ROE because banks borrow ~10× their equity. Big asset base, smaller equity sliver.
Note: this lens skips Altman Z-Score and Piotroski F-Score (validated on industrial companies, not banks). For deeper bank-specific health analysis: check the 10-K's Tier 1 capital ratio, Non-Performing Loan ratio, and CET1 — these are what regulators actually monitor.
Quality & solvency checks
Cheap stocks can be cheap for a reason. These screens warn when a low valuation comes paired with structural fragility.
Why it matters: Cheap-looking stocks (low P/E or P/B) often have low Z-scores because the market knows the company is dying. Z-score warns you before you fall into a value trap.
Reference: > 3.0 = safe zone · 1.81–3.0 = grey zone · < 1.81 = distress zone
Full explanation →
Altman Z was calibrated on industrial firms and doesn't apply to banks — the balance sheet is dominated by loans and securities, not working capital. See the Bank Valuation Lens above for P/TBV, ROTCE, P/B, ROE and ROA — the measures analysts in that industry actually use.
Why it matters: High score = fundamentals improving. Low score = deteriorating. Especially powerful for filtering cheap stocks: cheap + high F-score historically outperforms; cheap + low F-score is often a value trap.
Reference: 7–9 = strong · 4–6 = mediocre · 0–3 = weak
Full explanation →
Piotroski F was built for non-financial firms (gross margin, asset turnover and current ratio all assume an industrial cost structure). For banks the equivalent quality signals are the efficiency ratio, net interest margin and provision coverage — see the Bank Valuation Lens above.
BDRY is deeply overvalued by the model, trading at a premium of +221.2% to its intrinsic valueIntrinsic Value — Our DCF model's estimate of what each share is mathematically worth based on projected cash flows.
Why it matters: Compare to current price. Below IV = potentially undervalued. Above IV = priced for growth that must actually happen.
Reference: Model-derived; quality depends on data and assumptions.
Full explanation → of $4.029. The market appears to be paying for potential future returns from commodity trust investments, which are not fully captured by the backward-looking residual income model. The primary quantifiable risk is the negative net income in the latest period, indicating a lack of current profitability.
As of 3 months ago
Anatomy of a share
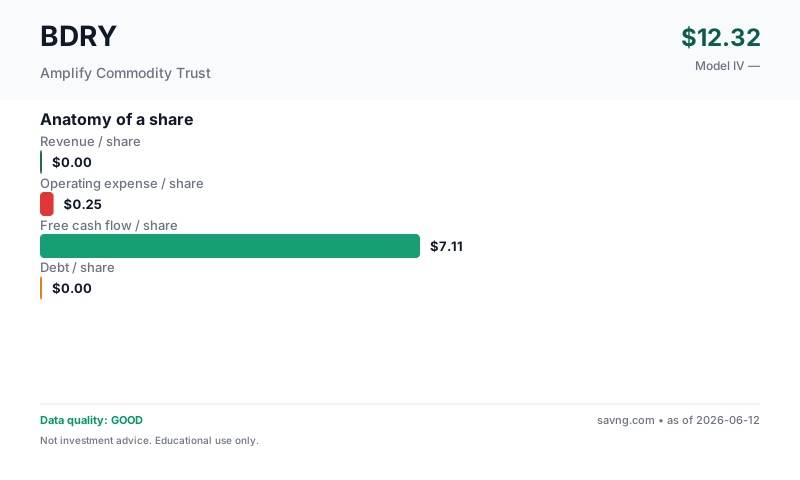
What you're buying per share. Bars are at the same scale so you can see the relative size of revenue, costs, cash flow, and debt — not just read them in a table.
What's free cash flow / what do these mean?
Revenue per share — how much the business earns from customers, divided by the number of shares outstanding. Top of the income statement.
Earnings per share — profit left after operating costs, interest, and taxes, per share. Two versions appear on this page and are not interchangeable: GAAP diluted EPS uses the company's weighted-average diluted share count during the reporting period (this is the "earnings" in "price-to-earnings"); net income per current share divides annual net income by today's share count. They differ whenever the share count has changed.
Owner-earnings free cash flow per share — the cash the business produces for shareholders. Savng's owner-earnings FCF subtracts capital expenditures and stock-based compensation from operating cash flow (SBC is a real dilution cost even though it's non-cash). This is deliberately more conservative than "standard" FCF, which subtracts only capital expenditures — so our figure is lower than the headline FCF you'll see elsewhere. FCF funds dividends, buybacks, debt repayment, and acquisitions; a company can report positive earnings yet negative FCF.
Debt per share — total interest-bearing borrowings divided by shares. High debt-per-share next to thin FCF-per-share is a fragility signal.
What you actually need to decide
Every stock price is a disagreement. Here's the single thing that must go right for the bulls, the single thing that breaks the thesis, and the concrete signposts to watch so you can update your view as real results arrive.
- Movement in global dry bulk shipping indices
- Quarterly net income turning positive
- Changes in global commodity demand forecasts
The trend, in plain numbers (FY2024 → FY2025, latest reported)
Straight from the financial statements — no model, no opinion. For a small or unprofitable company, the direction of these numbers usually tells you more than any single valuation.
- Free cash flow rose to $65.4M.
- Swung to a loss of -$17.5M (from a profit the prior year).
Management & Leadership
Limited executive data available for Amplify Commodity Trust. As an ETF, its management is typically handled by the fund sponsor, Amplify ETFs, which is led by CEO Christian Magoon.
What They Make
BDRY is an exchange-traded fund (ETF) that invests in a portfolio of freight futures contracts, providing exposure to the global shipping and dry bulk freight market. Its customers are investors seeking commodity exposure.
End Markets
Revenue Drivers
Why Is It Priced Like This?
Why Customers Pay
The market prices BDRY at a significant premium of +221.2% to the model's intrinsic valueIntrinsic Value — Our DCF model's estimate of what each share is mathematically worth based on projected cash flows.
Why it matters: Compare to current price. Below IV = potentially undervalued. Above IV = priced for growth that must actually happen.
Reference: Model-derived; quality depends on data and assumptions.
Full explanation →, likely anticipating future gains from its commodity trust investments that are not reflected in historical financial statements. While operating cash flow was positive in the latest period, the negative net income and a franchise/durability score of 0/5 suggest the market is assigning value to potential future market conditions or strategic positioning, which is not in the model.
Three Scenarios, Weighted
| Scenario | IV | Upside from today's price | Weight |
|---|---|---|---|
| Conservative | $3.98 | -74.7% | 40% |
| Base | $4.05 | -74.2% | 35% |
| Optimistic | $4.09 | -74.0% | 25% |
| Weighted | $4.03 | -74.4% | 100% |
Reading the last column: it is the move from today's price to each value (IV ÷ price − 1). The headline "premium/discount to model IV" measures the same gap from the value's side (price ÷ IV − 1), so the two percentages differ in size and sign by construction — e.g. a price 8% above value is a value 7.4% below price.
Business Model & Valuation
How They Make Money
As an ETF, BDRY typically distributes income to shareholders and reinvests capital according to its stated investment objectives, rather than engaging in buybacks or fixed dividends.
Residual Income High
Balance-sheet financial (Investment Banking): residual income model - book value is meaningful anchor.
Show advanced inputs
| Sector Default | 8.0% |
What this model does NOT do: this is a consolidated owner-earnings FCF model. Standalone segment assumptions: none. It does not project net interest income and fee-income lines independently; their combined effect is embedded in the historical revenue and cash-flow trend the model extrapolates. The calculator above can only approximate a segment's impact through the single consolidated growth rate — it cannot model any one line separately. For a true segment-level view, build a separate model from the company's segment disclosures.
Maturity & Competitive Position
Moat Signals
Net income has been negative in the latest period, though operating cash flow has been positive in 3 of the last 5 years.
Geography & Markets
As an ETF investing in global freight futures, BDRY's operations and underlying exposures are inherently global, reflecting worldwide shipping routes and commodity trade. Specific geographic revenue mix is not applicable for this investment vehicle.
Geographic Risks
Market Signals
These are timing signals, not value signals — they describe the stock's recent price behavior, not what the business is worth. Use them for the "the thesis looks good, but is now the moment?" question. Each tile below explains what it's saying.
Why it matters: Short-term contrarian indicator. Extreme readings often precede mean reversion, though not always.
Reference: 30–70 normal · >70 overbought · <30 oversold
Full explanation → (14)59.7NeutralMomentum is balanced — neither overbought nor oversold.
Why it matters: When the fast line crosses above the slow line, short-term momentum is turning up; below, turning down. A timing cue, not a value signal.
Reference: Line above signal = bullish momentum · below = bearish
Full explanation →BearishLine below signalThe fast trend is below the slow trend — short-term momentum is currently downward.
Technicals describe price, not the business. A great company can have a "bearish" tape (a buying chance) and a weak one a "bullish" tape (a trap). Pair these with the valuation and health sections above.
QUALITY
Data Quality & Risk Flags (4 notes — click to expand/collapse)
Guardrail Notes (4)
- Financial sector: using residual income model. IV = Book Value + PV(excess earnings).
- Discount rate floored from 7.5% to 9.0% (financial sector minimum).
- Terminal growth (3%) capped to 1.6% (80% of near-term growth 2%).
- Illiquidity discount 15% applied (small/micro-cap — harder to exit, demand a margin).
FINANCIALS
Financial Statements (5-year tables — click to expand)
From Amplify Commodity Trust's SEC filings (EDGAR).
Income (5yr)
| Year | Revenue | Net Income | EPS |
|---|---|---|---|
| 2025 | — | -17.5M | $-1.90 |
| 2024 | — | 46.5M | $5.05 |
| 2023 | — | -35.4M | $-3.84 |
| 2022 | — | -33.4M | $-3.63 |
| 2021 | — | 59.3M | $6.45 |
Cash Flow (5yr)
Capital expenditure isn't tagged in this filer's machine-readable data (the CapEx column shows "—"). The free-cash-flow column is therefore operating cash flow less stock-based compensation only — an upper bound on true owner earnings, not the real figure. Companies that report capex under a custom label (some large IFRS filers do) look better here than they are.
| Year | Operating CF | CapEx | − SBC & adj. | Free Cash Flow |
|---|---|---|---|---|
| 2024 | 65.4M | — | — | 65.4M |
| 2021 | 16.4M | — | — | 16.4M |
| 2020 | -2.5M | — | — | -2.5M |
| 2019 | 35.1M | — | — | 35.1M |
| 2018 | -32.3M | — | — | -32.3M |
How we define FCF: operating cash flow − capital expenditure − stock-based compensation (owner-earnings basis — SBC is a real cost to shareholders even though it's non-cash). This is the same owner-earnings FCF definition the valuation model uses, though the DCF's starting value is a EPS basis (residual-income model), not this single year.
Balance Sheet
| Total Assets | 68.6M |
| Total Liabilities | 1.4M |
| Equity | 67.1M |
Similar companies worth a look
Same sector and industry, similar fundamentals shape. Verify everything yourself — this list is computed mechanically and does not reflect our judgment about whether any of these are a good investment.