
Is Camden Property Trust (CPT) a good stock to buy?
Everything we have tested points the right way. That is a reason to look closer, not a reason to buy — these are frequencies about groups of companies in the past, not a statement about this one.
What each rating means, in numbers
Can it survive? — Very safe. Safer than 94% of the companies we cover, judged on the warning signs that came before companies that really did fail.
Business quality — Strong. Passes 6 of the 7 health checks we can measure — things like making a profit, turning it into cash, and not piling on debt. Across 131,000 company-quarters the weakest scorers went on to fail at 5.4% against 1.4% for the strongest, in every era and all twelve sectors.
How wild is the price? — Very calm. The share price swings about 22% in a typical year, which puts it in the calmest fifth. Out of every 100 companies that swung like this, about 0.3 went bankrupt within the year. Across the three periods we tested that ran from 0.1% to 0.7%.
What "tested" means here, and why there is no score out of 100
Tested means the read was measured against what actually happened afterwards, on a history that keeps the companies that were later delisted, using only figures that had been filed on the day they are used. Survival was ranked on companies that really did fail. What an owner keeps was tested across the universe from 2011 to 2025.
The full record of everything we have tested is on the research pages.
Which benchmark. Over the period we tested, the median listed company returned +5.8% a year while the S&P 500 returned about +13.9% — the index is weighted by size and was carried by a handful of enormous winners. So "beats the index" and "beats the other companies you could have bought" are different questions. Where a read says it picks better companies, it means the second one. None of these gets you an index fund's return, and we would rather say that than imply otherwise.
The quality read is the strongest thing we have tested: 131,000 company-quarters across 5,300 companies, where the weakest scorers went on to fail at 5.4% against 1.4% for the strongest, holding in every era and all twelve sectors. It still says less likely to break, not likely to beat the market — every band in that study lost to the index at the median, because the median listed company does.
Each read is shown on its own rather than merged into a single score, so you can see which part is strong and which is weak instead of taking an average on trust.
▾ What goes into the smart-money reading
Contributions (weight × component score) sum to the total. This near-term score now includes fundamental health (leverage, FCF trend, DCF applicability). It excludes the Altman Z score, whose retained-earnings input this filer does not report separately. See the Financial Health section for the full balance-sheet read.
Chance the S&P 500 falls 10% or more in the next three months.
Counted from every day since 2006. Says nothing about CPT — see the board for how it is measured.
📍 Where to start on this page, and what to look at first
How to read CPT (REIT)
REITs pay out most of their cash, so judge them on cash distributions and the value of their property — not on earnings or a standard DCF.
-
1
REIT lens (P/AFFO + dividend yield) ↓
Price-to-AFFO and the dividend yield are the real cheap/expensive gauges for real estate.
Is Camden Property Trust (CPT) overvalued?
Macro: Neutral / mid-cycleYes, by our measure: the price is about 36% above what we think the business is worth.
CPT trades at $98.00 vs an estimated intrinsic value of $71.83 — a +36.4% premium to model IV.
Not investment advice. The model can be wrong. Verify the assumptions in the sections below and consider consulting a licensed advisor for significant decisions.
What return would CPT pay as a bond?
Not measurable here. Valued on the dividend stream: the dividend itself is this security's coupon, and its yield is shown in the dividend lens. See the cross-company ranking →
Who owns CPT, and how it moves
From the SEC's own filings: every fund manager over $100M reports its holdings each quarter, and every officer and director reports theirs. Each point is what was public at the time.
573 institutions reported holding it at the latest quarter-end.
Safer than 94% of the stocks we cover
What this rating means, and what it does not
What this rank is — Very safe. Safer than 94% of the companies we cover. Out of every 100 companies ranked here, about <0.1% went bankrupt within the year, against 0.6% for the average company we cover. The rank comes from a model trained on every US filing since 2012, including 823 companies that really did fail, and scored each year by a version that had not seen that year.
What it is not — Not a trade. We tested shorting these names and buying puts, spreads, straddles and condors on them at real option prices, 2010-2025. Every version lost money: the market already prices the distress and the survivors squeeze. A high rank is a reason to read the filings and to size for a total loss, not a reason to bet against the company. A low rank says the balance sheet is calm, not that the price is sensible.
▾ The numbers, the logic, and why not to trade on it
The logic. A model trained on every US filing since 2012 — including 823 companies that went bankrupt or stopped trading under a dollar — ranks each covered stock by its chance of failing in the next year, from its latest filing, price history and credit conditions. The rank is a position among peers; the table is a count of what happened to stocks in each position, scored each year by a model that had not seen that year.
| Rank band | went bankrupt within 12 months | fell 80% or more (or failed) within 12 months | fell 50% or more (or failed) within 6 months |
|---|---|---|---|
| All covered stocks (average) | 0.59% | 4.21% | 8.51% |
| Finance (sector average) | 0.13% | 1.25% | 3.09% |
| riskiest 1% | 16.4% | 33.0% | 45.5% |
| next 2% (97-99) | 5.9% | 24.9% | 38.2% |
| next 2% (95-97) | 3.4% | 21.2% | 33.8% |
| next 5% (90-95) | 1.6% | 15.1% | 27.3% |
| next 15% (75-90) | 0.8% | 8.5% | 17.8% |
| next 25% (50-75) | 0.2% | 2.7% | 6.2% |
| safest half ← this stock | <0.1% | 0.5% | 2.1% |
Why not to trade on it. We tested shorting these names and buying puts, spreads, straddles and condors on them at real option prices, 2010–2025: every version lost money. The market already prices the distress, and the survivors squeeze. Use a high rank to read the filings and to size for a total loss — not to bet against the company. A low rank says the balance sheet is calm, not that the price is sensible.
Scored from the most recent SEC filing we had (dated 2026-05-04), which can be a quarterly report newer than the yearly figures used elsewhere on this page; scores last updated 2026-09-18. Within Finance: rank 8 of 100. Rough one-year odds for this stock alone: bankruptcy <0.1%, an 80% fall 0.2% (the model overstates the middle of the range).
▾ The logic, and why not to buy on it
The logic. Trained on 2,900 acquisitions since 2012, the model leans on size (small), age, retained earnings, asset growth, volatility and how many deals the sector has just seen. Announcement = the day the stock jumped, not the day the paperwork was filed.
| top 1% | 15.4% acquired within a year |
| next 2% (97-99) | 10.3% acquired within a year |
| next 2% (95-97) | 9.0% acquired within a year |
| next 5% (90-95) | 7.3% acquired within a year |
| next 15% (75-90) | 6.4% acquired within a year |
| next 25% (50-75) | 4.8% acquired within a year |
| bottom half ← this stock | 3.0% acquired within a year |
Why not to buy on it. A takeover paid a median +22% on the day — but even in the top band about 6 in 7 companies are not bought, and those lag. Buying the whole top list returned what the S&P 500 did (2012–2023), and adding "cheap" or "beaten-down" filters did not change that. Read it as context for a thesis you already have, never as the thesis.
What this rating means
What the rating says — Methods disagree. Methods disagree: the price is ABOVE 1 of 2 method ranges while inside the rest — assumption-sensitive, not clearly fair.
What it does not say — Not a forecast. This shows where today's price sits against several different ways of valuing the business. Where the methods disagree, the spread itself is the useful part - it tells you how much the answer depends on which one you trust.
Football field: where does the price sit?
Both bars below come from our own cash-flow model — one tries a range of growth rates, one shows our three scenarios. A third bar comparing CPT with similar companies appears only when there are enough close peers to trust it, and there aren't here. So this shows how much the answer depends on growth, not a set of independent checks.
Industry multiples sourced from: broad market average (sector unknown). See the Peer Basket section below for the peer comparison and its limited-comparables caveat.
How does CPT stack up against its closest peers?
We take the 8 same- or closely-related-industry companies closest in size to CPT and check what investors are paying for each dollar of their revenue (or profits). If CPT is much more expensive on the same yardstick, that's a red flag — unless you have a specific reason it deserves a premium. For a leveraged business, EV/EBIT and FCF yield (both in the table) are usually more reliable than EV/Sales, because revenue multiples ignore differences in margins and debt.
▾ What's "EV / Sales" in plain English?
EV (Enterprise Value) = market cap + total debt − cash. It's "what you'd pay to buy the entire company outright" — you pay the market cap to shareholders and take over their debt, but you keep their cash. EV is fairer than market cap alone because it includes the debt the new owner inherits.
EV / Sales = EV ÷ annual revenue. So "2.5×" means investors pay $2.50 of enterprise value per $1 of yearly sales. Higher = market is paying more per dollar of sales (usually because they expect future growth or fat margins).
p25 / median / p75 are the 25th, 50th (middle), and 75th percentile of the peers' multiples. Half the peers fall between p25 and p75. The median (p50) is the typical peer — that's the benchmark we compare to.
| EV / SalesEV / Sales — For every $1 of yearly revenue, this is how many dollars investors pay to own the whole business (including debt). Why it matters: Works for pre-profit growth companies where P/E and FCF don't apply. The most apples-to-apples cross-company multiple because it ignores accounting choices. Reference: 1–3x for mature companies · 4–10x for software/SaaS · 10–20x for hypergrowth · >20x is rare and demanding Full explanation → |
4.0x / 5.7x / 12.2x |
| EV / EBITEV / EBITDA — Enterprise value divided by earnings before interest, tax, depreciation, and amortization. Why it matters: A classic "what would a private buyer pay" multiple — used in M&A. Strips out tax and capital-structure noise. Reference: 8–12x for mature businesses · 15–25x for growth · Below 5x often signals distress Full explanation → |
14.0x / 14.9x / 28.1x |
Bold middle number = median peer. Half the peers trade above it, half below. Computed over 8 same-industry peers; implausible multiples excluded.
⚠️ Important caveat: peer multiples only work if the peers are genuinely comparable. Always check the peer list below — if the auto-picker grabbed micro-caps or unrelated businesses, the comparison is noise. A medical-device giant priced against tiny biotech startups won't produce a useful signal.
▾ View peer list (8)
| Ticker | Company | Industry | Mcap | EV/Sales | EV/GP | EV/EBIT | FCF Yield |
|---|---|---|---|---|---|---|---|
| REXR | Rexford Industrial Realty, Inc. | REITs | $8.5B | 11.7x | — | — | 4.5% |
| SUI | SUN COMMUNITIES INC | REITs | $15.2B | 6.6x | — | — | 0.9% |
| RHP | Ryman Hospitality Properties, Inc. | REITs | $7.3B | 2.8x | — | 14.9x | 3.8% |
| STAG | STAG Industrial, Inc. | REITs | $7.0B | 12.2x | — | — | 4.0% |
| WPC | W. P. Carey Inc. | REITs | $16.6B | 14.7x | — | — | 4.8% |
| SSRM | SSR MINING INC. | REITs | $6.5B | 4.0x | — | 14.0x | 3.0% |
| VNO | VORNADO REALTY TRUST | REITs | $6.4B | 4.8x | — | — | 2.2% |
| OUT | OUTFRONT Media Inc. | REITs | $5.7B | 4.5x | — | 28.1x | 3.9% |
Real-estate-specific metrics
REITs are valued on AFFO (Adjusted Funds from Operations) and dividend yield, not DCF. Reported depreciation isn't a real cash cost for real estate — properties typically hold or appreciate. The metrics below are the industry-standard yardsticks.
Note: Depreciation & Amortization line not available — using FCF/share as AFFO proxy. Directionally correct but understates true AFFO (true AFFO adds back D&A and subtracts only maintenance CapEx; FCF subtracts all CapEx).
Quality & solvency checks
Cheap stocks can be cheap for a reason. These screens warn when a low valuation comes paired with structural fragility.
What these health ratings mean, in numbers
Business quality — Strong. Passes 6 of the 7 health checks we can measure — making a profit, turning it into cash, not piling on debt, not issuing shares. Across 131,000 company-quarters the weakest scorers went on to fail at 5.4% within a year against 1.4% for the strongest, and that held in every era and all twelve sectors. It says "less likely to break", not "likely to beat the market".
Why it matters: Cheap-looking stocks (low P/E or P/B) often have low Z-scores because the market knows the company is dying. Z-score warns you before you fall into a value trap.
Reference: > 3.0 = safe zone · 1.81–3.0 = grey zone · < 1.81 = distress zone
Full explanation →
REITs deliberately carry high leverage backed by long-life real estate and pay out 90%+ of taxable income — both inputs that Altman Z flags as distress. See the REIT Valuation Lens above for P/AFFO, dividend yield and payout ratio.
Why it matters: High score = fundamentals improving. Low score = deteriorating. Especially powerful for filtering cheap stocks: cheap + high F-score historically outperforms; cheap + low F-score is often a value trap.
Reference: 7–9 = strong · 4–6 = mediocre · 0–3 = weak
Full explanation →
Piotroski F's checks (operating cash flow, gross-margin trend, current ratio, asset turnover) assume an industrial cost structure, so they misread asset-heavy or financial businesses like this one — a healthy REIT, utility, pipeline, BDC/fund or holding company can score low for reasons that aren't weakness. See the sector lens above for the metrics that actually matter.
What if you assume different inputs?
Here's where we land — and what happens if you change the assumptions. Drag the sliders to set your own Discount RateDiscount Rate — The annual return you demand for taking single-stock risk instead of buying a safe Treasury or index fund.
Why it matters: Higher discount rate = stricter valuation (a stock has to produce more cash to be worth holding). Lower = more generous.
Reference: 8–12% is standard · 9–10% matches S&P 500 historical return · Below 7% is illogical for single-stock risk
Full explanation → (the annual return you demand for single-stock risk) and terminal growth; the value updates live so you can see whether the stock looks cheaper or richer. The discount rate starts at 10.0%, the figure our model used for CPT. Open Advanced to also change beta, growth and the rate path.
Note: the calculator opens at our published value of $71.83 — it is initialised to the same scenario-weighted result, so the two match exactly on load. The moment you move a slider, the value below becomes a single-path what-if at your assumptions (not the three-scenario weighting), which is why it can differ from the headline once you've touched it.
8.5% — beta-based (CAPM), from this stock's BetaBeta — How much the stock moves when the overall market moves. 1.0 = moves with the market; 1.5 = moves 50% more than the market.
Why it matters: Higher beta = more volatile = should demand higher discount rate. Low beta stocks (utilities, consumer staples) move less.
Reference: Most stocks 0.5–1.5 · Defensives ~0.3 · High-vol tech ~1.5–2.0
Full explanation → of 0.55. The safe Treasury rate plus a premium scaled by how much more (or less) volatile the stock is than the market.
10.0% — sector/quality tier. A simpler hurdle set by industry and business durability: lower for stable, wide-moat companies; higher for speculative or micro-caps.
The headline value and this calculator start at 10.0% — the more conservative sector/quality rate (we use the more conservative sector/quality rate when model applicability is limited or the balance sheet is stretched). Drag the slider to the other rate to see the full range.
CPT is valued with a dividend-discount model. The calculator above starts from that published value and shows how it moves with the discount rate and long-run growth; it does not rebuild the model year by year. The sector lens shows the measures that matter most for this kind of business.
—
⚙ Advanced — tinker with every input (beta, growth, rate path, margin → full intrinsic value)
Camden Property Trust is deeply overvalued, with the price 36.4% above intrinsic valueIntrinsic Value — Our DCF model's estimate of what each share is mathematically worth based on projected cash flows.
Why it matters: Compare to current price. Below IV = potentially undervalued. Above IV = priced for growth that must actually happen.
Reference: Model-derived; quality depends on data and assumptions.
Full explanation → (a 36.4% premium). The market appears to be paying for the company's consistent profitability and positive operating cash flow, despite a low franchise/durability score of 1/5. The biggest risk that our model's base assumptions prove too high is the continuing rise in long-term debt, which has increased from $3.2 billion to $3.9 billion.
As of 20 days ago
Anatomy of a share
What you're buying per share. Bars are at the same scale so you can see the relative size of revenue, costs, cash flow, and debt — not just read them in a table.
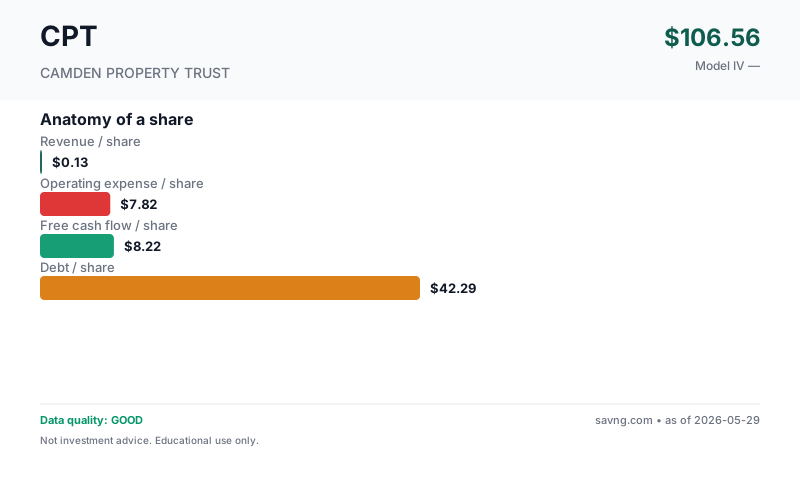
What's free cash flow / what do these mean?
Revenue per share — how much the business earns from customers, divided by the number of shares outstanding. Top of the income statement.
Earnings per share — profit left after operating costs, interest, and taxes, per share. Two versions appear on this page and are not interchangeable: GAAP diluted EPS uses the company's weighted-average diluted share count during the reporting period (this is the "earnings" in "price-to-earnings"); net income per current share divides annual net income by today's share count. They differ whenever the share count has changed.
Owner-earnings free cash flow per share — the cash the business produces for shareholders. Savng's owner-earnings FCF subtracts capital expenditures and stock-based compensation from operating cash flow (SBC is a real dilution cost even though it's non-cash). This is deliberately more conservative than "standard" FCF, which subtracts only capital expenditures — so our figure is lower than the headline FCF you'll see elsewhere. FCF funds dividends, buybacks, debt repayment, and acquisitions; a company can report positive earnings yet negative FCF.
Debt per share — total interest-bearing borrowings divided by shares. High debt-per-share next to thin FCF-per-share is a fragility signal.
What you actually need to decide
Every stock price is a disagreement. Here's the single thing that must go right for the bulls, the single thing that breaks the thesis, and the concrete signposts to watch so you can update your view as real results arrive.
- Quarterly occupancy rates and rental growth trends
- Changes in long-term debt levels
- Operating cash flow per share trends
The trend, in plain numbers (FY2024 → FY2025, latest reported)
Straight from the financial statements — no model, no opinion. For a small or unprofitable company, the direction of these numbers usually tells you more than any single valuation.
- Revenue grew +82% to $13.0M.
- Free cash flow rose to $807.2M.
- Net income grew +135% to $384.5M.
Nothing was clearly worsening year-over-year.
Management & Leadership
Alexander J. Jessett serves as the President & CFO, while Richard J Campo is the Executive Chairman. D Keith Oden holds the position of Executive Vice Chairman, and Michael P Gallagher is the Chief Accounting Officer.
President & CFO
Executive Chairman
What They Make
Camden Property Trust is a real estate investment trust (REITREIT (Real Estate Investment Trust) — A company that owns income-producing real estate and is required to pay out about 90% of its profit to shareholders as dividends.
Why it matters: Because they pay out almost everything, REITs are judged on the cash they distribute (price-to-AFFO and dividend yield), not on ordinary earnings — a normal P/E or DCF misleads here.
Reference: Dividend yields often 3–6%; valued on price-to-AFFO, not P/E.
Full explanation →) that owns, manages, develops, and acquires multifamily residential properties. Their paying customers are the tenants who rent their apartment units.
End Markets
Revenue Drivers
Why Is It Priced Like This?
Why Customers Pay
The market prices CPT at a premium of +36.4% to the model's intrinsic valueIntrinsic Value — Our DCF model's estimate of what each share is mathematically worth based on projected cash flows.
Why it matters: Compare to current price. Below IV = potentially undervalued. Above IV = priced for growth that must actually happen.
Reference: Model-derived; quality depends on data and assumptions.
Full explanation →, likely due to its consistent profitability (net income positive 5/5 yrs) and positive operating cash flow (positive 5/5 yrs). This suggests investors are willing to pay for the stability and income generation of its real estate portfolio, despite the low franchise/durability score of 1/5.
Three Scenarios, Weighted
| Scenario | IV | Upside from today's price | Weight |
|---|---|---|---|
| Conservative | $61.80 | -36.9% | 40% |
| Base | $73.03 | -25.5% | 35% |
| Optimistic | $86.18 | -12.1% | 25% |
| Weighted | $71.83 | -26.7% | 100% |
Reading the last column: it is the move from today's price to each value (IV ÷ price − 1). The headline "premium/discount to model IV" measures the same gap from the value's side (price ÷ IV − 1), so the two percentages differ in size and sign by construction — e.g. a price 8% above value is a value 7.4% below price.
Business Model & Valuation
How They Make Money
The company declared a dividend of $4.2/yr per share in the last fiscal year, with dividend growth of 6%/yr over 5 years. Long-term debt is rising, from $3.2 billion to $3.9 billion.
Dividend Discount Medium
REIT (REITs): dividend discount model - GAAP earnings distort REIT valuations.
Show advanced inputs
What this model does NOT do: this is a consolidated dividend-discount model. Standalone segment assumptions: none. It does not project net interest income and fee-income lines independently; their combined effect is embedded in the historical revenue and cash-flow trend the model extrapolates. The calculator above can only approximate a segment's impact through the single consolidated growth rate — it cannot model any one line separately. For a true segment-level view, build a separate model from the company's segment disclosures.
Maturity & Competitive Position
Moat Signals
Revenue has been growing at 5.3%/yr over 4 years, from $11M to $13.0 million.
Geography & Markets
Geographic Risks
Market Signals
These are timing signals, not value signals — they describe the stock's recent price behavior, not what the business is worth. Use them for the "the thesis looks good, but is now the moment?" question. Each tile below explains what it's saying.
Why it matters: Short-term contrarian indicator. Extreme readings often precede mean reversion, though not always.
Reference: 30–70 normal · >70 overbought · <30 oversold
Full explanation → (14)27.1OversoldHeavily sold off recently — sometimes a bounce setup, sometimes a falling knife.
Why it matters: When the fast line crosses above the slow line, short-term momentum is turning up; below, turning down. A timing cue, not a value signal.
Reference: Line above signal = bullish momentum · below = bearish
Full explanation →BearishLine below signalThe fast trend is below the slow trend — short-term momentum is currently downward.
Technicals describe price, not the business. A great company can have a "bearish" tape (a buying chance) and a weak one a "bullish" tape (a trap). Pair these with the valuation and health sections above.
QUALITY
Data Quality & Risk Flags (3 notes — click to expand/collapse)
Guardrail Notes (3)
- Dividend: last fiscal-year DECLARED dividend per share from the filing ($4.2/yr, us-gaap:CommonStockDividendsPerShareDeclared).
- Dividend growth from the declared-DPS series: 6%/yr over 5 years.
- Dividend data sparse; DDM using estimated yield. Confidence reduced.
FINANCIALS
Financial Statements (5-year tables — click to expand)
From Camden Property Trust's SEC filings (EDGAR).
Income (5yr)
| Year | Revenue | Net Income | EPS |
|---|---|---|---|
| 2025 | 13.0M | 384.5M | $3.54 |
| 2024 | 7.1M | 163.3M | $1.50 |
| 2023 | 3.5M | 403.3M | $3.70 |
| 2022 | 5.2M | 653.6M | $6.04 |
| 2021 | 10.5M | 303.9M | $2.96 |
Cash Flow (5yr)
| Year | Operating CF | CapEx | − SBC | Free Cash Flow |
|---|---|---|---|---|
| 2025 | 826.6M | 2.4M | 17.0M | 807.2M |
| 2024 | 774.9M | 3.8M | 15.2M | 755.9M |
| 2023 | 795.0M | 5.6M | 14.5M | 774.8M |
| 2022 | 744.7M | 4.4M | 12.8M | 727.5M |
| 2021 | 577.5M | 4.0M | 15.4M | 558.0M |
How we define FCF: operating cash flow − capital expenditure − stock-based compensation (owner-earnings basis — SBC is a real cost to shareholders even though it's non-cash). Latest year: 826.6M − 2.4M − 17.0M (stock-based comp) = 807.2M. This is the same owner-earnings FCF definition the valuation model uses, though the DCF's starting value is a TTM dividend, not this single year.
Balance Sheet
| Total Assets | 9.0B |
| Total Liabilities | 4.6B |
| Equity | 4.4B |
| Total Debt | 3.9B |
Similar companies worth a look
Same sector and industry, similar fundamentals shape. Verify everything yourself — this list is computed mechanically and does not reflect our judgment about whether any of these are a good investment.
The questions people ask about CPT
Is Camden Property Trust (CPT) a good stock to buy?
Camden Property Trust (CPT) looks expensive against its own cash flows: the price is about 36% above our $71.83 estimate. Whether it is a good buy depends on whether the company can grow faster than that price assumes, on its financial health, and on what insiders are doing. All three are on this page. This is educational research from SEC filings, not investment advice.
Is Camden Property Trust (CPT) overvalued?
Yes, by our measure. Camden Property Trust (CPT) trades at $98.00, about 36% above our estimate of $71.83 for what the business is worth. This is educational research from SEC filings, not investment advice.
What is CPT's intrinsic value?
Our model estimates CPT is worth about $71.83 per share, built from the cash the business is expected to generate, taken from its SEC filings. The market price is $98.00.
Where do these numbers come from?
From Camden Property Trust's own SEC filings (10-K and 10-Q), Form 4 insider filings and daily market prices. Every figure on the page links to how it was calculated, and the model's weak spots are listed next to its results.