
Is Currenc Group Inc. (CURR) a good stock to buy?
What we have tested leans negative. To like it anyway you need a reason our checks do not capture.
What each rating means, in numbers
Business quality — Middling. Passes 6 of the 9 health checks we can measure — things like making a profit, turning it into cash, and not piling on debt. Across 131,000 company-quarters the weakest scorers went on to fail at 5.4% against 1.4% for the strongest, in every era and all twelve sectors.
How wild is the price? — Very wild. The share price swings about 90% in a typical year, which puts it in the most volatile fifth. Out of every 100 companies that swung like this, about 8.6 went bankrupt within the year. Across the three periods we tested that ran from 3.7% to 11.5%.
What "tested" means here, and why there is no score out of 100
Tested means the read was measured against what actually happened afterwards, on a history that keeps the companies that were later delisted, using only figures that had been filed on the day they are used. Survival was ranked on companies that really did fail. What an owner keeps was tested across the universe from 2011 to 2025.
The full record of everything we have tested is on the research pages.
Which benchmark. Over the period we tested, the median listed company returned +5.8% a year while the S&P 500 returned about +13.9% — the index is weighted by size and was carried by a handful of enormous winners. So "beats the index" and "beats the other companies you could have bought" are different questions. Where a read says it picks better companies, it means the second one. None of these gets you an index fund's return, and we would rather say that than imply otherwise.
The quality read is the strongest thing we have tested: 131,000 company-quarters across 5,300 companies, where the weakest scorers went on to fail at 5.4% against 1.4% for the strongest, holding in every era and all twelve sectors. It still says less likely to break, not likely to beat the market — every band in that study lost to the index at the median, because the median listed company does.
Each read is shown on its own rather than merged into a single score, so you can see which part is strong and which is weak instead of taking an average on trust.
▾ What goes into the smart-money reading
Contributions (weight × component score) sum to the total. This near-term score now includes fundamental health (leverage, FCF trend, DCF applicability). It excludes the Altman Z score, whose retained-earnings input this filer does not report separately. See the Financial Health section for the full balance-sheet read.
Chance the S&P 500 falls 10% or more in the next three months.
Counted from every day since 2006. Says nothing about CURR — see the board for how it is measured.
📍 Where to start on this page, and what to look at first
How to read CURR
CURR generates real cash flow, but the DCF here is a low-confidence estimate — the value is sensitive to how we normalize cash flow, cyclicality, and secular/industry risk. Treat the DCF as one input, then pressure-test it against the reverse-DCF, leverage, and the operating trends below.
-
1
The verdict + intrinsic value (our DCF) ↓
Our estimate of what a share is worth, versus today's price.
-
2
Reverse-DCF + the interactive calculator ↓
See the growth the price assumes, then flex every assumption yourself to pressure-test it.
-
3
Football field + peers ↓
A cross-check across methods and against comparable companies.
Who owns CURR, and how it moves
From the SEC's own filings: every fund manager over $100M reports its holdings each quarter, and every officer and director reports theirs. Each point is what was public at the time.
11 institutions reported holding it at the latest quarter-end.
What growth must the market believe? Reverse DCF — Instead of asking "what is this stock worth?", asks "what growth rate is the current market price already assuming?"
Why it matters: It crystallizes the bull thesis as a single number you can argue with. If the market expects 40% growth for 10 years and you do not believe that, the stock is overvalued.
Reference: 10–15% = sustainable for strong companies · 20–25% = exceptional · 30%+ = historically very rare
Traditional DCF asks "what is this stock worth?" Reverse DCF flips it: it treats today's price as correct and solves for the growth rate that justifies it. In plain terms — if our model is right about everything else, the company's cash flow would have to grow (or shrink) by this much every year for the next 5 years for today's price to make sense. If that required growth looks unrealistic, the price is stretched; if it looks easy to beat, the price may be cheap.
Why it matters: A company can show big profits on paper while burning through cash. FCF is what actually fills the bank account.
Reference: Healthy mature businesses convert 8–15% of revenue into FCF · Growth companies often negative
Full explanation → must grow at:
▾ Exactly how this 5-year figure is computed
Forecast length: 5 years at the solved rate, then a linear fade to terminal growth over years 6-10 — the same shape the DCF above uses
Terminal growth after the fade: 2.9%
Discount rate: 13.0% (the rate the model used)
Price used: $2.77 — the live price shown on this page (not frozen)
Method: solve for the constant annual growth rate that makes the discounted 10-year FCF stream + terminal value equal today's price.
Very few companies have compounded cash flow at this rate for five years. The market is pricing a near-best-case outcome.
For reference: Heroic — very few companies have ever compounded cash flow this fast at scale for a decade. The price leaves no room for error.
▾ How we computed this · Reality check thresholds · Assumptions
- Starting FCF/share: $0.06 (TTM)
- Discount RateDiscount Rate — The annual return you demand for taking single-stock risk instead of buying a safe Treasury or index fund.
Why it matters: Higher discount rate = stricter valuation (a stock has to produce more cash to be worth holding). Lower = more generous.
Reference: 8–12% is standard · 9–10% matches S&P 500 historical return · Below 7% is illogical for single-stock risk
Full explanation →: 13.0% — standard 8-12%; 9-10% matches S&P 500 historical return - Terminal Growth RateTerminal Growth Rate — The growth rate we assume the company holds forever, after the explicit 10-year forecast period ends.
Why it matters: It anchors the long-tail value. Cannot mathematically exceed long-term GDP growth or the company eventually becomes larger than the global economy.
Reference: 2–3% (matches long-term US GDP growth) · Above 4% is mathematically problematic
Full explanation →: 2.9% — matches long-term GDP growth - Forecast horizon: 10 years explicit + terminal perpetuity
| ≤ 0% | Priced for decline — likely undervalued OR dying business |
| 5-12% | Reasonable; sustainable for quality businesses |
| 12-18% | Demanding — strong execution required |
| 18-25% | Exceptional — few companies sustain for a decade |
| 25-35% | Heroic — historically very rare |
| 35%+ | Borderline impossible at scale |
Sustaining 30%+ cash-flow growth for a full decade at scale is exceedingly rare — the bar is brutally high.
Use the interactive calculator below to change the discount rate, growth and terminal-growth assumptions and watch the value move.
What this rating means
What the rating says — Above every method. The current price sits ABOVE the high end of every method. The market is paying a premium to all of these lenses — it expects materially better growth or margins than the models assume.
What it does not say — Not a forecast. This shows where today's price sits against several different ways of valuing the business. Where the methods disagree, the spread itself is the useful part - it tells you how much the answer depends on which one you trust.
Football field: where does the price sit?
Both bars below come from our own cash-flow model — one tries a range of growth rates, one shows our three scenarios. A third bar comparing CURR with similar companies appears only when there are enough close peers to trust it, and there aren't here. So this shows how much the answer depends on growth, not a set of independent checks.
Industry multiples sourced from: sector: Technology. See the Peer Basket section below for the peer comparison and its limited-comparables caveat.
How does CURR stack up against its closest peers?
We take the 4 same- or closely-related-industry companies closest in size to CURR and check what investors are paying for each dollar of their revenue (or profits). If CURR is much more expensive on the same yardstick, that's a red flag — unless you have a specific reason it deserves a premium. For a leveraged business, EV/EBIT and FCF yield (both in the table) are usually more reliable than EV/Sales, because revenue multiples ignore differences in margins and debt.
▾ What's "EV / Sales" in plain English?
EV (Enterprise Value) = market cap + total debt − cash. It's "what you'd pay to buy the entire company outright" — you pay the market cap to shareholders and take over their debt, but you keep their cash. EV is fairer than market cap alone because it includes the debt the new owner inherits.
EV / Sales = EV ÷ annual revenue. So "2.5×" means investors pay $2.50 of enterprise value per $1 of yearly sales. Higher = market is paying more per dollar of sales (usually because they expect future growth or fat margins).
p25 / median / p75 are the 25th, 50th (middle), and 75th percentile of the peers' multiples. Half the peers fall between p25 and p75. The median (p50) is the typical peer — that's the benchmark we compare to.
Bold middle number = median peer. Half the peers trade above it, half below. Computed over 4 same-industry peers; implausible multiples excluded.
⚠️ Important caveat: peer multiples only work if the peers are genuinely comparable. Always check the peer list below — if the auto-picker grabbed micro-caps or unrelated businesses, the comparison is noise. A medical-device giant priced against tiny biotech startups won't produce a useful signal.
▾ View peer list (8)
| Ticker | Company | Industry | Mcap | EV/Sales | EV/GP | EV/EBIT | FCF Yield |
|---|---|---|---|---|---|---|---|
| RGP | RESOURCES CONNECTION, INC. | Business Services | $155M | 0.3x | 0.7x | — | 6.3% |
| IRHOU | Iron Horse Acquisition II Corp. | Business Services | $298M | — | — | — | — |
| RYDE | Ryde Group Ltd | Business Services | $87M | 8.9x | — | — | 2.3% |
| IMXI | International Money Express, Inc. | Business Services | $345M | 0.9x | — | 9.7x | 14.0% |
| UXIN | Uxin Ltd | Business Services ·fallback | $251M | 0.5x | 8.1x | — | 100.0% |
| POWW | Outdoor Holding Co | Business Services ·fallback | $259M | 5.3x | 6.0x | — | 1.9% |
| OPRX | OptimizeRx Corp | Business Services ·fallback | $97M | 1.1x | 1.7x | 10.6x | 11.9% |
| ZH | Zhihu Inc. | Business Services ·fallback | $313M | 0.8x | 1.3x | — | 10.0% |
Quality & solvency checks
Cheap stocks can be cheap for a reason. These screens warn when a low valuation comes paired with structural fragility.
What these health ratings mean, in numbers
Business quality — Middling. Passes 6 of the 9 health checks we can measure — things like making a profit, turning it into cash, and not piling on debt. Across 131,000 company-quarters the weakest scorers went on to fail at 5.4% within a year against 1.4% for the strongest, and that held in every era and all twelve sectors. It says "less likely to break", not "likely to beat the market".
Why it matters: Cheap-looking stocks (low P/E or P/B) often have low Z-scores because the market knows the company is dying. Z-score warns you before you fall into a value trap.
Reference: > 3.0 = safe zone · 1.81–3.0 = grey zone · < 1.81 = distress zone
Full explanation →
We can't produce a trustworthy Altman Z here: retained earnings weren't separately reported in our data, so a core input would have to be fabricated. Rather than show a categorical "distress" verdict from an invented number, we mark it unavailable. The classic manufacturing-calibrated model also fits asset-light businesses like this one poorly. Judge financial health from the leverage, cash position, and the measurable Piotroski checks instead.
Why it matters: High score = fundamentals improving. Low score = deteriorating. Especially powerful for filtering cheap stocks: cheap + high F-score historically outperforms; cheap + low F-score is often a value trap.
Reference: 7–9 = strong · 4–6 = mediocre · 0–3 = weak
Full explanation →
▾ The checks — what passed, what didn't (and what we couldn't measure)
-
✗ Positive net incomeNet income -$18.4M in FY2025.Why this matters: Does the company actually earn a profit? Sustained losses eventually force it to raise money — diluting you — or take on debt.
-
✓ Positive operating cash flowOperating cash flow $7.9M (was $3.5M the prior year).
-
✓ Cash flow backs up reported profitOperating cash flow $7.9M vs net income -$18.4M.
-
✓ Return on assets improvingReturn on assets -16.2% vs -37.7% a year ago.
-
✓ Debt load (vs assets)Total debt is 1.0% of assets vs 3.5% a year ago ($1.2M of $114.1M assets).
-
✓ Short-term liquidity (current ratio)Current ratio 1.12x vs 0.60x a year ago.
-
✗ Share count (dilution)Share count rose 61.1% (38.2M → 61.5M year-over-year).Why this matters: Issuing lots of new shares splits the pie into more pieces, shrinking your slice. Stable or falling share count protects existing owners.
-
✓ Pricing power (gross margin)Gross margin 40.8% vs 31.4% a year ago.
-
✗ Sales per asset (asset turnover)Asset turnover 0.33x vs 0.44x a year ago.Why this matters: Asset turnover measures how much revenue each dollar of assets generates. Rising = more productive use of the asset base.
Missing data is never counted as a pass or a fail — it's shown as n/a and excluded from the denominator. Each check compares the company against its own prior year.
What if you assume different inputs?
Here's where we land — and what happens if you change the assumptions. Drag the sliders to set your own Discount RateDiscount Rate — The annual return you demand for taking single-stock risk instead of buying a safe Treasury or index fund.
Why it matters: Higher discount rate = stricter valuation (a stock has to produce more cash to be worth holding). Lower = more generous.
Reference: 8–12% is standard · 9–10% matches S&P 500 historical return · Below 7% is illogical for single-stock risk
Full explanation → (the annual return you demand for single-stock risk) and terminal growth; the value updates live so you can see whether the stock looks cheaper or richer. The discount rate starts at 13.0%, the figure our model used for CURR. Open Advanced to also change beta, growth and the rate path.
Note: the calculator opens at our published value of $0.49 — it is initialised to the same scenario-weighted result, so the two match exactly on load. The moment you move a slider, the value below becomes a single-path what-if at your assumptions (not the three-scenario weighting), which is why it can differ from the headline once you've touched it.
8.5% — beta-based (CAPM), from this stock's BetaBeta — How much the stock moves when the overall market moves. 1.0 = moves with the market; 1.5 = moves 50% more than the market.
Why it matters: Higher beta = more volatile = should demand higher discount rate. Low beta stocks (utilities, consumer staples) move less.
Reference: Most stocks 0.5–1.5 · Defensives ~0.3 · High-vol tech ~1.5–2.0
Full explanation → of 0.67. The safe Treasury rate plus a premium scaled by how much more (or less) volatile the stock is than the market.
13.0% — sector/quality tier. A simpler hurdle set by industry and business durability: lower for stable, wide-moat companies; higher for speculative or micro-caps.
The headline value and this calculator start at 13.0% — the more conservative sector/quality rate (we use the more conservative sector/quality rate when model applicability is limited or the balance sheet is stretched). Drag the slider to the other rate to see the full range.
+461.9%
At the default assumptions the flat path lands near our published value of $0.49. Move any slider to recompute it with your own.
Move any slider above to recompute this against your own assumptions.
⚙ Advanced — tinker with every input (beta, growth, rate path, margin → full intrinsic value)
Currenc Group Inc. is well above the model value; the price is 461.9% above intrinsic valueIntrinsic Value — Our DCF model's estimate of what each share is mathematically worth based on projected cash flows.
Why it matters: Compare to current price. Below IV = potentially undervalued. Above IV = priced for growth that must actually happen.
Reference: Model-derived; quality depends on data and assumptions.
Full explanation → (a 461.9% premium). The market appears to be paying up for significant future growth potential, as evidenced by the implied growth rate of 35.1% compared to the model's 3.7%. The biggest risk to our model's base assumptions is that the company's operating cash flow, which was positive at $7.9 million latest but only positive 2/4 years, declines rather than growing at the modeled rate.
As of today
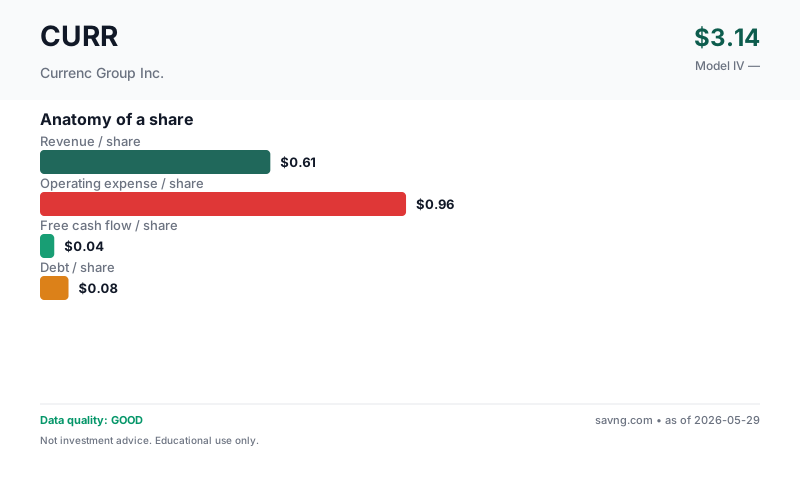
Anatomy of a share
What you're buying per share. Bars are at the same scale so you can see the relative size of revenue, costs, cash flow, and debt — not just read them in a table.
What's free cash flow / what do these mean?
Revenue per share — how much the business earns from customers, divided by the number of shares outstanding. Top of the income statement.
Earnings per share — profit left after operating costs, interest, and taxes, per share. Two versions appear on this page and are not interchangeable: GAAP diluted EPS uses the company's weighted-average diluted share count during the reporting period (this is the "earnings" in "price-to-earnings"); net income per current share divides annual net income by today's share count. They differ whenever the share count has changed.
Owner-earnings free cash flow per share — the cash the business produces for shareholders. Savng's owner-earnings FCF subtracts capital expenditures and stock-based compensation from operating cash flow (SBC is a real dilution cost even though it's non-cash). This is deliberately more conservative than "standard" FCF, which subtracts only capital expenditures — so our figure is lower than the headline FCF you'll see elsewhere. FCF funds dividends, buybacks, debt repayment, and acquisitions; a company can report positive earnings yet negative FCF.
Debt per share — total interest-bearing borrowings divided by shares. High debt-per-share next to thin FCF-per-share is a fragility signal.
What you actually need to decide
Every stock price is a disagreement. Here's the single thing that must go right for the bulls, the single thing that breaks the thesis, and the concrete signposts to watch so you can update your view as real results arrive.
Why it matters: It's a real cost — it dilutes your ownership — so we subtract it from free cash flow even though accounting rules add it back, which would otherwise flatter cash-heavy tech companies.
Reference: Can be 10–30% of revenue at high-growth software firms.
Full explanation → free cash flowFree Cash Flow (FCF) — Operating cash flow minus capital spending: cash left after a company covers operating costs, taxes and interest and reinvests in the business — but BEFORE repaying debt principal or paying dividends. The cash actually available to investors.
Why it matters: A company can show big profits on paper while burning through cash. FCF is what actually fills the bank account.
Reference: Healthy mature businesses convert 8–15% of revenue into FCF · Growth companies often negative
Full explanation →.
- Next quarter's operating cash flow trend
- Improvement in net income profitability
- Any announcements regarding new service offerings or market expansion
The trend, in plain numbers (FY2024 → FY2025, latest reported)
Straight from the financial statements — no model, no opinion. For a small or unprofitable company, the direction of these numbers usually tells you more than any single valuation.
- Free cash flow turned positive at $3.4M.
- Gross margin improved to 41% (+9 pts).
- Still unprofitable at -$18.4M — loss narrowing.
- Revenue fell -19% to $37.8M.
Management & Leadership
Ronnie Ka Wah Hui serves as the Chief Executive Officer, and Eng Ho Ng is the Chief Financial Officer. Kevin Chen and Eric David Weinstein are also listed as Directors.
Chief Executive Officer
Chief Financial Officer
What They Make
Currenc Group Inc. operates in the Business Services industry within the Technology sector. The company provides various business services, though specific products are not detailed in the available information. The paying counterparties would be businesses utilizing their services.
End Markets
Why Is It Priced Like This?
The market prices CURR at a premium of +461.9%, implying a significant future growth trajectory of 35.1% annually in per-share cash flow. This optimism is despite the company's net income being negative in the latest fiscal year and only profitable in 0/4 years, and its operating cash flow being positive in only 2/4 years. The market may be assigning value to potential new service offerings or expansion into high-growth business service niches, which is not in the model.
Three Scenarios, Weighted
| Scenario | IV | Upside from today's price | Weight |
|---|---|---|---|
| Conservative | $0.43 | -84.4% | 40% |
| Base | $0.50 | -81.9% | 35% |
| Optimistic | $0.59 | -78.8% | 25% |
| Weighted | $0.49 | -82.2% | 100% |
Reading the last column: it is the move from today's price to each value (IV ÷ price − 1). The headline "premium/discount to model IV" measures the same gap from the value's side (price ÷ IV − 1), so the two percentages differ in size and sign by construction — e.g. a price 8% above value is a value 7.4% below price.
Business Model & Valuation
How They Make Money
The company funds itself through its operating cash flow, which was $7.9 million latest, and holds $75.2 million in cash and short-term investments. Stock-based compensation equals 54% of pre-SBCSBC (Stock-Based Compensation) — Paying employees with company shares instead of cash.
Why it matters: It's a real cost — it dilutes your ownership — so we subtract it from free cash flow even though accounting rules add it back, which would otherwise flatter cash-heavy tech companies.
Reference: Can be 10–30% of revenue at high-growth software firms.
Full explanation → free cash flowFree Cash Flow (FCF) — Operating cash flow minus capital spending: cash left after a company covers operating costs, taxes and interest and reinvests in the business — but BEFORE repaying debt principal or paying dividends. The cash actually available to investors.
Why it matters: A company can show big profits on paper while burning through cash. FCF is what actually fills the bank account.
Reference: Healthy mature businesses convert 8–15% of revenue into FCF · Growth companies often negative
Full explanation →, and the company retires ~4.0%/yr of its shares.
Free Cash Flow DCF Low
Owner-earnings FCF DCF: positive free cash flow (operating cash flow − capex − stock-based comp) in a sector suited for cash-flow-based valuation. FCF negative in 3/4 years. High P/FCF (64x) - market pricing significant growth.
▾ Why is DCF applicability "Low" for CURR?
- Declining recent results (revenue declining), which a backward-looking model struggles to price.
- Individual business-segment drivers are not forecast separately — the model works off consolidated cash flow only.
Because of this, we headline the more conservative discount rate and urge you to weight the reverse-DCF, leverage, and operating trends alongside the DCF.
Show advanced inputs
| Revenue Growth | -15.7% |
| Sector Default | 12.0% |
| Sector Default Source | Technology sector default |
| Best Estimate | 3.7% |
| Method | blend(30% revenue_cagr, 70% sector) (buybacks ~4%/yr: per-share support, not added to growth) |
| Growth Basis | total |
| Business Growth | 3.7% |
| Buyback Rate | 4.0% |
What this model does NOT do: this is a consolidated owner-earnings cash-flow model. Standalone segment assumptions: none. It does not project product, services and recurring/cloud lines independently; their combined effect is embedded in the historical revenue and cash-flow trend the model extrapolates. The calculator above can only approximate a segment's impact through the single consolidated growth rate — it cannot model any one line separately. For a true segment-level view, build a separate model from the company's segment disclosures.
Maturity & Competitive Position
Revenue was $37.8 million in the latest fiscal year, but net income has been negative in the latest period and only profitable in 0/4 years.
Market Signals
These are timing signals, not value signals — they describe the stock's recent price behavior, not what the business is worth. Use them for the "the thesis looks good, but is now the moment?" question. Each tile below explains what it's saying.
Why it matters: Short-term contrarian indicator. Extreme readings often precede mean reversion, though not always.
Reference: 30–70 normal · >70 overbought · <30 oversold
Full explanation → (14)41.5NeutralMomentum is balanced — neither overbought nor oversold.
Why it matters: When the fast line crosses above the slow line, short-term momentum is turning up; below, turning down. A timing cue, not a value signal.
Reference: Line above signal = bullish momentum · below = bearish
Full explanation →BearishLine below signalThe fast trend is below the slow trend — short-term momentum is currently downward.
Technicals describe price, not the business. A great company can have a "bearish" tape (a buying chance) and a weak one a "bullish" tape (a trap). Pair these with the valuation and health sections above.
QUALITY
Data Quality & Risk Flags (5 notes — click to expand/collapse)
Guardrail Notes (4)
- Stock-based compensation equals 54% of pre-SBC free cash flow; FCF used here is net of SBC (a real shareholder-dilution cost), so it is lower than the headline GAAP cash-flow figure.
- The company retires ~4%/yr of its shares (a multi-year CAGR), but we do NOT add that to the growth rate: buybacks at fair value are value-neutral per current share, and adding them would double-count the same cash the DCF already values. We also do not model future buyback ACCRETION: repurchases below intrinsic value CAN raise value per remaining share, but only if they continue, are funded after debt service, and are made below intrinsic value — excluding that potential benefit keeps the model conservative.
- Terminal growth set to 2.9% — the lowest of the applicable caps (binding: 80% of near-term growth (3.7%)). We use one effective terminal rate everywhere on the page.
- Illiquidity discount 15% applied (small/micro-cap — harder to exit, demand a margin).
FINANCIALS
Financial Statements (5-year tables — click to expand)
From Currenc Group Inc.'s SEC filings (EDGAR).
Income (5yr)
| Year | Revenue | Net Income | EPS |
|---|---|---|---|
| 2025 | 37.8M | -18.4M | $-0.30 |
| 2024 | 46.4M | -39.5M | $-1.03 |
| 2023 | 53.3M | -15.3M | $-0.45 |
| 2022 | — | -1.1M | $-0.01 |
Cash Flow (5yr)
| Year | Operating CF | CapEx | − SBC | Free Cash Flow |
|---|---|---|---|---|
| 2025 | 7.9M | 479,034 | 4.0M | 3.4M |
| 2024 | 3.5M | 576,674 | 20.9M | -18.0M |
| 2023 | -15.3M | 291,856 | — | -15.6M |
| 2022 | -756,716 | 3.0M | — | -3.8M |
How we define FCF: operating cash flow − capital expenditure − stock-based compensation (owner-earnings basis — SBC is a real cost to shareholders even though it's non-cash). Latest year: 7.9M − 479,034 − 4.0M (stock-based comp) = 3.4M. This is the same owner-earnings FCF definition the valuation model uses.
Balance Sheet
| Total Assets | 114.1M |
| Total Liabilities | 95.4M |
| Equity | -5.7M |
| Total Debt | 1.2M |
Similar companies worth a look
Same sector and industry, similar fundamentals shape. Verify everything yourself — this list is computed mechanically and does not reflect our judgment about whether any of these are a good investment.
The questions people ask about CURR
Is Currenc Group Inc. (CURR) a good stock to buy?
Currenc Group Inc. (CURR) looks expensive against its own cash flows: the price is about 462% above our $0.49 estimate. Whether it is a good buy depends on whether the company can grow faster than that price assumes, on its financial health, and on what insiders are doing. All three are on this page. This is educational research from SEC filings, not investment advice.
Is Currenc Group Inc. (CURR) overvalued?
Yes, by our measure. Currenc Group Inc. (CURR) trades at $2.77, about 462% above our estimate of $0.49 for what the business is worth. This is educational research from SEC filings, not investment advice.
What is CURR's intrinsic value?
Our model estimates CURR is worth about $0.49 per share, built from the cash the business is expected to generate, taken from its SEC filings. The market price is $2.77.
What growth is priced into CURR?
Working backwards from today's price, the market expects CURR's cash flow per share to grow by roughly 35.1% a year over the next five years. Compare that with the company's actual record on this page.
Where do these numbers come from?
From Currenc Group Inc.'s own SEC filings (10-K and 10-Q), Form 4 insider filings and daily market prices. Every figure on the page links to how it was calculated, and the model's weak spots are listed next to its results.