
Megan Holdings Ltd. (MGN) Stock Analysis
Megan Holdings Ltd.
▾ What's in the 58/100 risk score? (higher = riskier)
Contributions (weight × component score) sum to the total. This near-term score now includes fundamental health (leverage, FCF trend, DCF applicability). It excludes the Altman Z score, whose retained-earnings input this filer does not report separately. See the Financial Health section for the full balance-sheet read.
How to read MGN (speculative micro-cap)
No model can pin a precise fair value on a company this small — but that does not mean there is nothing to learn. The useful questions are what the price is betting on, and whether the company can survive long enough to deliver it.
-
1
Reverse-DCF — what growth the price assumes ↓
The single most useful number here: it backs out the growth the market is paying for. If that figure is "historically unprecedented," the price is running on hype, not fundamentals.
-
2
Cash runway ↓
A pre-profit micro-cap lives or dies on whether it can fund itself to profitability before running out of money and diluting you.
-
3
The raw financial statements + the 10-K ↓
At this scale, the actual numbers, insider ownership, and share-count trend tell you more than any ratio.
Is now a good time to buy MGN?
Macro: Neutral / mid-cycle
MGN trades at $0.13 vs an estimated
intrinsic value
of $0.07
— a +90.7% premium to model IV.
Today's price is consistent with MGN's owner-earnings free cash flow per share growing about 14.9% per year 5-YR · SCENARIO PATH over the next 5 years (the
price-implied growth rate).
Our DCF projects
modeled growth
of 5.0% per year based on history + sector defaults
(analyst consensus estimates not yet integrated).
Note: this is a 5-year, per-share view. The Reverse-DCF section below asks the same question on a stricter 10-year free-cash-flowFree Cash Flow (FCF) — Operating cash flow minus capital spending: cash left after a company covers operating costs, taxes and interest and reinvests in the business — but BEFORE repaying debt principal or paying dividends. The cash actually available to investors.
Why it matters: A company can show big profits on paper while burning through cash. FCF is what actually fills the bank account.
Reference: Healthy mature businesses convert 8–15% of revenue into FCF · Growth companies often negative
Full explanation → basis — so its growth number is different, not contradictory.
▾ Exactly how this 5-year figure is computed
Current price: $0.13 (live)
Discount rate: 15.1%; terminal growth: 2.5%
Forecast: 5 years explicit growth, then a linear fade to terminal; end-of-period cash flows discounted to today
Growth path: the model's scenario-weighted path (conservative 40% / base 35% / optimistic 25% — assumed weights, not measured probabilities) — see the "Three Scenarios, Weighted" table below for the three IVs
Method: solve for the constant 5-year per-share growth rate that, run through this same structure, makes the intrinsic value equal today's price. (The 10-year figure below uses a flat 10-yr path instead — hence a different number.)
Not investment advice. The model can be wrong. Verify the assumptions in the sections below and consider consulting a licensed advisor for significant decisions.
What return would MGN pay as a bond?
Not measurable here. Only 0 years of positive owner earnings in the record (we require 3) — not enough history to treat the cash flow as a coupon. For the record, today's owner-earnings yield is 7.8% on the model's starting cash flow. See the cross-company ranking →
What cash-flow improvement must the market believe? Reverse DCF — Instead of asking "what is this stock worth?", asks "what growth rate is the current market price already assuming?"
Why it matters: It crystallizes the bull thesis as a single number you can argue with. If the market expects 40% growth for 10 years and you do not believe that, the stock is overvalued.
Reference: 10–15% = sustainable for strong companies · 20–25% = exceptional · 30%+ = historically very rare
Reverse DCF treats today's price as correct and solves for the cash-flow path that justifies it. For a cyclical, read the result as the annual improvement in through-cycle free cash flow the price requires — which could come from higher realized commodity prices, margin recovery, lower input costs, more volume, or reduced capex, not just organic growth. The starting base is our normalized mid-cycle median, not last year's number.
Why it matters: A company can show big profits on paper while burning through cash. FCF is what actually fills the bank account.
Reference: Healthy mature businesses convert 8–15% of revenue into FCF · Growth companies often negative
Full explanation → must improve by:
▾ Exactly how this 10-year figure is computed
Forecast length: 10 years, single flat growth rate (no fade)
Terminal growth after year 10: 2.5%
Discount rate: 15.1% (the rate the model used)
Price used: $0.13 — the live price shown on this page (not frozen)
Method: solve for the constant annual growth rate that makes the discounted 10-year FCF stream + terminal value equal today's price.
Within range of what a quality mature business can sustainably deliver. Not demanding.
For reference: Reasonable — sustainable for a quality business over time.
▾ How we computed this · Reality check thresholds · Assumptions
- Starting FCF/share: $0.01 (mid-cycle estimate (median operating cash flow less estimated maintenance capex and stock compensation — by design NOT the table's FCF, which deducts every year's full capex))
- Discount RateDiscount Rate — The annual return you demand for taking single-stock risk instead of buying a safe Treasury or index fund.
Why it matters: Higher discount rate = stricter valuation (a stock has to produce more cash to be worth holding). Lower = more generous.
Reference: 8–12% is standard · 9–10% matches S&P 500 historical return · Below 7% is illogical for single-stock risk
Full explanation →: 15.1% — standard 8-12%; 9-10% matches S&P 500 historical return - Terminal Growth RateTerminal Growth Rate — The growth rate we assume the company holds forever, after the explicit 10-year forecast period ends.
Why it matters: It anchors the long-tail value. Cannot mathematically exceed long-term GDP growth or the company eventually becomes larger than the global economy.
Reference: 2–3% (matches long-term US GDP growth) · Above 4% is mathematically problematic
Full explanation →: 2.5% — matches long-term GDP growth - Forecast horizon: 10 years explicit + terminal perpetuity
| ≤ 0% | Priced for decline — likely undervalued OR dying business |
| 5-12% | Reasonable; sustainable for quality businesses |
| 12-18% | Demanding — strong execution required |
| 18-25% | Exceptional — few companies sustain for a decade |
| 25-35% | Heroic — historically very rare |
| 35%+ | Borderline impossible at scale |
Sustaining 30%+ cash-flow growth for a full decade at scale is exceedingly rare — the bar is brutally high.
Use the interactive calculator below to change the discount rate, growth and terminal-growth assumptions and watch the value move.
⚠ At today's price, the market values MGN at about 0.1× its annual sales — a typical established company trades around 1–3×. Standard industry multiples (the bars below) collapse toward $0 at this scale, so they aren't the useful read. For a micro-cap with sales, lean on the Reverse-DCF (what revenue growth that price implies), the Momentum trend, and cash runway — see 📍 What to focus on.
Football field: where does the price sit?
Different valuation methods produce different fair-value ranges depending on assumptions. Plotting them together lets you see at a glance whether the current price is reasonable across approaches, or only one specific lens.
Industry multiples sourced from: broad market average (sector unknown). See the Peer Basket section below for the peer comparison and its limited-comparables caveat.
How to read a company this small
MGN is too small and/or too volatile for the valuation lenses we use on larger, more stable companies. The numbers shown below should be taken as rough orientation only.
- Market cap $2.0M — nano-cap territory (below $50M)
Growth percentages on tiny revenue bases (1000% going from $200K to $2M is not predictive). P/E and ROE swing wildly with small earnings changes. Peer comparisons fail because there often aren't comparable companies at this scale.
Start with the Reverse-DCF above — it backs out the growth the price is betting on; if that figure is "historically unprecedented," the price is running on hype, not fundamentals. Then the cash runway (can it fund itself to profitability before diluting you?). Then the raw Financials table and the 10-K on SEC EDGAR — at this scale, insider ownership and the share-count trend often matter more than any ratio.
Classified as Speculative Nano / Micro-cap (confidence 80%). Disagree? An admin can override via the post edit screen.
⚠ Genuine comparables are scarce at this size, so peer multiples are unreliable here. Treat as rough context only — see 📍 What to focus on above.
How does MGN stack up against its closest peers?
Ideally we compare MGN only to same-industry peers, but too few exist in our universe right now, so the basket below mixes in broader-sector names. Treat the multiples as rough context, not a valuation. For a leveraged business, FCF yield (in the table) is usually more reliable than EV/Sales, because revenue multiples ignore differences in margins and debt.
▾ What's "EV / Sales" in plain English?
EV (Enterprise Value) = market cap + total debt − cash. It's "what you'd pay to buy the entire company outright" — you pay the market cap to shareholders and take over their debt, but you keep their cash. EV is fairer than market cap alone because it includes the debt the new owner inherits.
EV / Sales = EV ÷ annual revenue. So "2.5×" means investors pay $2.50 of enterprise value per $1 of yearly sales. Higher = market is paying more per dollar of sales (usually because they expect future growth or fat margins).
p25 / median / p75 are the 25th, 50th (middle), and 75th percentile of the peers' multiples. Half the peers fall between p25 and p75. The median (p50) is the typical peer — that's the benchmark we compare to.
| EV / SalesEV / Sales — For every $1 of yearly revenue, this is how many dollars investors pay to own the whole business (including debt). Why it matters: Works for pre-profit growth companies where P/E and FCF don't apply. The most apples-to-apples cross-company multiple because it ignores accounting choices. Reference: 1–3x for mature companies · 4–10x for software/SaaS · 10–20x for hypergrowth · >20x is rare and demanding Full explanation → |
0.1x / 0.3x / 4.1x |
| EV / Gross ProfitEV / Gross Profit — Enterprise value divided by gross profit — the multiple paid for what each dollar of sales contributes after direct costs. Why it matters: More refined than EV/Sales for high-margin businesses (software, marketplaces) where gross margin is the real economic engine. Reference: 8–15x for SaaS · 15–25x for hypergrowth software · >30x demanding Full explanation → |
0.4x / 6.6x / 21.1x |
Bold middle number = median peer. Half the peers trade above it, half below. Computed over 4 peers (broad — see caveat); implausible multiples excluded.
⚠️ Important caveat: peer multiples only work if the peers are genuinely comparable. Always check the peer list below — if the auto-picker grabbed micro-caps or unrelated businesses, the comparison is noise. A medical-device giant priced against tiny biotech startups won't produce a useful signal.
▾ View peer list (4)
| Ticker | Company | Industry | Mcap | EV/Sales | EV/GP | EV/EBIT | FCF Yield |
|---|---|---|---|---|---|---|---|
| NCRA | NOCERA, INC. | Agricultural Prod-Livestoc | $3M | 0.3x | 21.1x | — | 4.5% |
| TANH | TANTECH HOLDINGS LTD | Industrial Organic Chemica ·fallback | $3M | 0.1x | 0.4x | — | 428.0% |
| SDSTW | Stardust Power Inc. | Nonferrous Metals ·fallback | $1M | — | — | — | 8.2% |
| SNES | SenesTech, Inc. | Agricultural Chemicals ·fallback | $9M | 4.1x | 6.6x | — | 0.6% |
Quality & solvency checks
Cheap stocks can be cheap for a reason. These screens warn when a low valuation comes paired with structural fragility.
Why it matters: Cheap-looking stocks (low P/E or P/B) often have low Z-scores because the market knows the company is dying. Z-score warns you before you fall into a value trap.
Reference: > 3.0 = safe zone · 1.81–3.0 = grey zone · < 1.81 = distress zone
Full explanation →
We can't produce a trustworthy Altman Z here: retained earnings weren't separately reported in our data, so a core input would have to be fabricated. Rather than show a categorical "distress" verdict from an invented number, we mark it unavailable. Judge financial health from the leverage, cash position, and the measurable Piotroski checks instead.
Why it matters: High score = fundamentals improving. Low score = deteriorating. Especially powerful for filtering cheap stocks: cheap + high F-score historically outperforms; cheap + low F-score is often a value trap.
Reference: 7–9 = strong · 4–6 = mediocre · 0–3 = weak
Full explanation →
The F-score compares two consecutive years of income, cash-flow and balance-sheet data. This filer is missing individual line items the checks depend on. We show nothing rather than score a partial year against itself. The reported figures in the financial tables below are unaffected.
What if you assume different inputs?
Here's where we land — and what happens if you change the assumptions. Drag the sliders to set your own Discount RateDiscount Rate — The annual return you demand for taking single-stock risk instead of buying a safe Treasury or index fund.
Why it matters: Higher discount rate = stricter valuation (a stock has to produce more cash to be worth holding). Lower = more generous.
Reference: 8–12% is standard · 9–10% matches S&P 500 historical return · Below 7% is illogical for single-stock risk
Full explanation → (the annual return you demand for single-stock risk) and terminal growth; the value updates live so you can see whether the stock looks cheaper or richer. The discount rate starts at 15.1%, the figure our model used for MGN. Open Advanced to also change beta, growth and the rate path.
Note: the calculator opens at our published value of $0.07 — it is initialised to the same scenario-weighted result, so the two match exactly on load. The moment you move a slider, the value below becomes a single-path what-if at your assumptions (not the three-scenario weighting), which is why it can differ from the headline once you've touched it.
15.1% — beta-based (CAPM), from this stock's BetaBeta — How much the stock moves when the overall market moves. 1.0 = moves with the market; 1.5 = moves 50% more than the market.
Why it matters: Higher beta = more volatile = should demand higher discount rate. Low beta stocks (utilities, consumer staples) move less.
Reference: Most stocks 0.5–1.5 · Defensives ~0.3 · High-vol tech ~1.5–2.0
Full explanation → of 1.93. The safe Treasury rate plus a premium scaled by how much more (or less) volatile the stock is than the market.
14.0% — sector/quality tier. A simpler hurdle set by industry and business durability: lower for stable, wide-moat companies; higher for speculative or micro-caps.
The headline value and this calculator start at 15.1% — the beta-based rate. Drag the slider to the other rate to see the full range.
+90.7%
At the default assumptions the flat path lands near our published value of $0.07. Move any slider to recompute it with your own.
Move any slider above to recompute this against your own assumptions.
⚙ Advanced — tinker with every input (beta, growth, rate path, margin → full intrinsic value)
MGN is deeply overvalued, trading at a premium of +117.8% to the model's intrinsic valueIntrinsic Value — Our DCF model's estimate of what each share is mathematically worth based on projected cash flows.
Why it matters: Compare to current price. Below IV = potentially undervalued. Above IV = priced for growth that must actually happen.
Reference: Model-derived; quality depends on data and assumptions.
Full explanation →. The market appears to be paying for future growth, with an implied growth rate of 14.9% compared to the model's 5.0%. However, this optimism is not supported by current health signals, particularly the negative operating cash flow in the latest period. The number one quantifiable risk is the negative operating cash flow, which makes the normalized FCFFree Cash Flow (FCF) — Operating cash flow minus capital spending: cash left after a company covers operating costs, taxes and interest and reinvests in the business — but BEFORE repaying debt principal or paying dividends. The cash actually available to investors.
Why it matters: A company can show big profits on paper while burning through cash. FCF is what actually fills the bank account.
Reference: Healthy mature businesses convert 8–15% of revenue into FCF · Growth companies often negative
Full explanation → less reliable.
As of 3 months ago
Anatomy of a share
What you're buying per share. Bars are at the same scale so you can see the relative size of revenue, costs, cash flow, and debt — not just read them in a table.
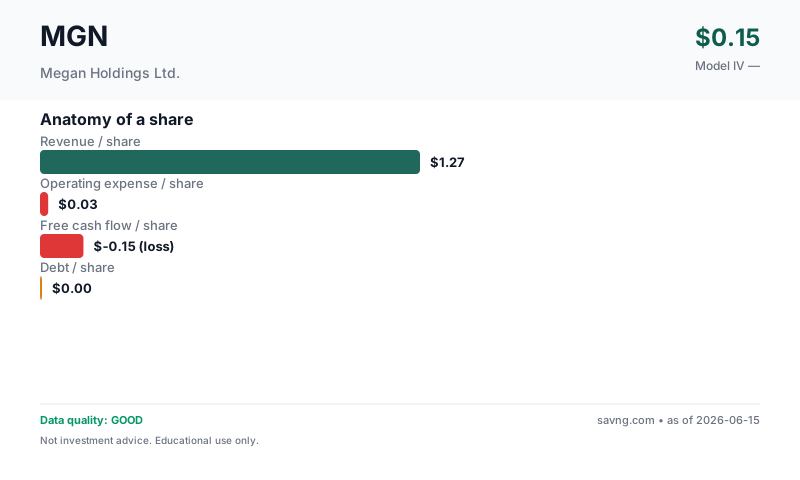
What's free cash flow / what do these mean?
Revenue per share — how much the business earns from customers, divided by the number of shares outstanding. Top of the income statement.
Earnings per share — profit left after operating costs, interest, and taxes, per share. Two versions appear on this page and are not interchangeable: GAAP diluted EPS uses the company's weighted-average diluted share count during the reporting period (this is the "earnings" in "price-to-earnings"); net income per current share divides annual net income by today's share count. They differ whenever the share count has changed.
Owner-earnings free cash flow per share — the cash the business produces for shareholders. Savng's owner-earnings FCF subtracts capital expenditures and stock-based compensation from operating cash flow (SBC is a real dilution cost even though it's non-cash). This is deliberately more conservative than "standard" FCF, which subtracts only capital expenditures — so our figure is lower than the headline FCF you'll see elsewhere. FCF funds dividends, buybacks, debt repayment, and acquisitions; a company can report positive earnings yet negative FCF.
Debt per share — total interest-bearing borrowings divided by shares. High debt-per-share next to thin FCF-per-share is a fragility signal.
What you actually need to decide
Every stock price is a disagreement. Here's the single thing that must go right for the bulls, the single thing that breaks the thesis, and the concrete signposts to watch so you can update your view as real results arrive.
- Operating cash flow turning positive in the next reporting period.
- Consistent net income profitability over multiple quarters.
- Reduction in long-term debt or stable debt levels.
Management & Leadership
Limited executive data available. Megan Holdings Ltd. is a relatively obscure company, and specific executive details are not widely publicized or available in current data.
What They Make
Megan Holdings Ltd. operates in the agricultural products sector, specializing in livestock and animal specialties. They likely provide products or services related to animal husbandry and agricultural production.
End Markets
Revenue Drivers
Why Is It Priced Like This?
Why Customers Pay
The market prices MGN at a premium of +117.8%, implying a growth rate of 14.9% compared to the model's 5.0%. This suggests investors are anticipating significant future growth or a turnaround, despite the company's operating cash flow being negative in the latest period and only being profitable in 1 out of 3 years. The market's optimism is not clearly justified by the current health signals.
Three Scenarios, Weighted
| Scenario | IV | Upside from today's price | Weight |
|---|---|---|---|
| Conservative | $0.06 | -53.4% | 40% |
| Base | $0.07 | -47.6% | 35% |
| Optimistic | $0.08 | -35.9% | 25% |
| Weighted | $0.07 | -47.6% | 100% |
Reading the last column: it is the move from today's price to each value (IV ÷ price − 1). The headline "premium/discount to model IV" measures the same gap from the value's side (price ÷ IV − 1), so the two percentages differ in size and sign by construction — e.g. a price 8% above value is a value 7.4% below price.
Business Model & Valuation
How They Make Money
The company's long-term debt is rising, from $0M to $0M, indicating it may be funding operations or growth through debt, though the absolute amounts are negligible. No specific dividend or buyback rates are available.
Normalized FCF High
Cyclical/commodity sector (Agricultural Prod-Livestock & Animal Specialties) with negative current FCF: normalized FCF uses multi-year median to smooth through the cycle.
Show advanced inputs
| Sector Default | 5.0% |
| Best Estimate | 5.0% |
| Method | sector_default |
| Growth Basis | total |
What this model does NOT do: this is a consolidated owner-earnings FCF model. Standalone segment assumptions: none. It does not project production volumes, realized commodity prices and unit cash costs independently; their combined effect is embedded in the historical revenue and cash-flow trend the model extrapolates. The calculator above can only approximate a segment's impact through the single consolidated growth rate — it cannot model any one line separately. For a true segment-level view, build a separate model from the company's segment disclosures.
Maturity & Competitive Position
Net income has been positive in 1 out of 3 years, indicating inconsistent profitability.
Geography & Markets
Limited geographic mix data is available. Megan Holdings Ltd. likely operates within specific regional agricultural markets, but the exact breakdown of its operations is not provided in current filings.
Geographic Risks
Market Signals
These are timing signals, not value signals — they describe the stock's recent price behavior, not what the business is worth. Use them for the "the thesis looks good, but is now the moment?" question. Each tile below explains what it's saying.
Why it matters: Short-term contrarian indicator. Extreme readings often precede mean reversion, though not always.
Reference: 30–70 normal · >70 overbought · <30 oversold
Full explanation → (14)33.1NeutralMomentum is balanced — neither overbought nor oversold.
Why it matters: When the fast line crosses above the slow line, short-term momentum is turning up; below, turning down. A timing cue, not a value signal.
Reference: Line above signal = bullish momentum · below = bearish
Full explanation →BullishLine above signalThe fast trend is above the slow trend — short-term momentum is currently upward.
Technicals describe price, not the business. A great company can have a "bearish" tape (a buying chance) and a weak one a "bullish" tape (a trap). Pair these with the valuation and health sections above.
QUALITY
Data Quality & Risk Flags (7 notes — click to expand/collapse)
Guardrail Notes (6)
- Median OCF is negative — OCF-based normalization not applicable.
- Limited cash flow history (1yr) — normalized FCF is less reliable.
- Normalized OCF-capex was negative. Falling back to median raw FCF.
- No positive normalized FCF. Using EPS as proxy.
- Model implies no positive equity value under these assumptions. Valuation is speculative/low-confidence.
- Illiquidity discount 25% applied (small/micro-cap — harder to exit, demand a margin).
FINANCIALS
Financial Statements (5-year tables — click to expand)
From Megan Holdings Ltd.'s SEC filings (EDGAR).
Income (5yr)
| Year | Revenue | Net Income | EPS |
|---|---|---|---|
| 2025 | 20.7M | 216,823 | $0.01 |
| 2024 | — | — | $0.00 |
| 2023 | — | — | $0.00 |
Cash Flow (5yr)
| Year | Operating CF | CapEx | − SBC & adj. | Free Cash Flow |
|---|---|---|---|---|
| 2025 | -2.4M | 64 | — | -2.4M |
How we define FCF: operating cash flow − capital expenditure − stock-based compensation (owner-earnings basis — SBC is a real cost to shareholders even though it's non-cash). This is the same owner-earnings FCF definition the valuation model uses, though the DCF's starting value is a mid-cycle estimate (median operating cash flow less estimated maintenance capex and stock compensation — by design NOT the table's FCF, which deducts every year's full capex), not this single year.
Balance Sheet
| Total Assets | 23.3M |
| Total Liabilities | 11.4M |
| Equity | 11.9M |
| Total Debt | 80,370 |