
REGENCY CENTERS CORP (REG) Stock Analysis
REGENCY CENTERS CORP
▾ What's in the 54/100 risk score? (higher = riskier)
Contributions (weight × component score) sum to the total. This near-term score now includes fundamental health (leverage, FCF trend, DCF applicability). It excludes the Altman Z score, whose retained-earnings input this filer does not report separately. See the Financial Health section for the full balance-sheet read.
Nothing we have tested argues against it, and one read argues for it. Worth reading further.
What "tested" means here, and why there is no score out of 100
Tested means the read was measured against what actually happened afterwards, on a history that keeps the companies that were later delisted, using only figures that had been filed on the day they are used. Survival was ranked on companies that really did fail. What an owner keeps was tested across the universe from 2011 to 2025. A valuation finding appears only when the cheap fifth of that business type beat the index — 156 of the 206 combinations we tried did not.
Not tested means we compute it and find it useful, but we have never measured whether it predicts anything. Our own model valuation is in that category. It is shown, and it does not decide the verdict.
There is no single score because we have not tested one. Combining five reads into one number implies somebody checked that the combination works, and nobody has. When that test exists, a number can appear here.
📍 Where to start on this page, and what to look at first
How to read REG (REIT)
REITs pay out most of their cash, so judge them on cash distributions and the value of their property — not on earnings or a standard DCF.
-
1
REIT lens (P/AFFO + dividend yield) ↓
Price-to-AFFO and the dividend yield are the real cheap/expensive gauges for real estate.
Is now a good time to buy REG?
Macro: Neutral / mid-cycleREG trades at $72.95 vs an estimated intrinsic value of $74.58 — a 2.2% gap.
Not investment advice. The model can be wrong. Verify the assumptions in the sections below and consider consulting a licensed advisor for significant decisions.
What return would REG pay as a bond?
Not measurable here. Valued on the dividend stream: the dividend itself is this security's coupon, and its yield is shown in the dividend lens. See the cross-company ranking →
Safer than 94% of the stocks we cover
▾ The numbers, the logic, and why not to trade on it
The logic. A model trained on every US filing since 2012 — including 823 companies that went bankrupt or stopped trading under a dollar — ranks each covered stock by its chance of failing in the next year, from its latest filing, price history and credit conditions. The rank is a position among peers; the table is a count of what happened to stocks in each position, scored each year by a model that had not seen that year.
| Rank band | went bankrupt within 12 months | fell 80% or more (or failed) within 12 months | fell 50% or more (or failed) within 6 months |
|---|---|---|---|
| All covered stocks (average) | 0.59% | 4.21% | 8.51% |
| Finance (sector average) | 0.13% | 1.25% | 3.09% |
| riskiest 1% | 16.4% | 33.0% | 45.5% |
| next 2% (97-99) | 5.9% | 24.9% | 38.2% |
| next 2% (95-97) | 3.4% | 21.2% | 33.8% |
| next 5% (90-95) | 1.6% | 15.1% | 27.3% |
| next 15% (75-90) | 0.8% | 8.5% | 17.8% |
| next 25% (50-75) | 0.2% | 2.7% | 6.2% |
| safest half ← this stock | <0.1% | 0.5% | 2.1% |
Why not to trade on it. We tested shorting these names and buying puts, spreads, straddles and condors on them at real option prices, 2010–2025: every version lost money. The market already prices the distress, and the survivors squeeze. Use a high rank to read the filings and to size for a total loss — not to bet against the company. A low rank says the balance sheet is calm, not that the price is sensible.
Scored from the filing of 2026-05-05; table generated 2026-09-18. Within Finance: rank 9 of 100. Rough one-year odds for this stock alone: bankruptcy <0.1%, an 80% fall 0.3% (the model overstates the middle of the range).
▾ The logic, and why not to buy on it
The logic. Trained on 2,900 acquisitions since 2012, the model leans on size (small), age, retained earnings, asset growth, volatility and how many deals the sector has just seen. Announcement = the day the stock jumped, not the day the paperwork was filed.
| top 1% | 15.4% acquired within a year |
| next 2% (97-99) | 10.3% acquired within a year |
| next 2% (95-97) | 9.0% acquired within a year |
| next 5% (90-95) | 7.3% acquired within a year |
| next 15% (75-90) | 6.4% acquired within a year |
| next 25% (50-75) | 4.8% acquired within a year |
| bottom half ← this stock | 3.0% acquired within a year |
Why not to buy on it. A takeover paid a median +22% on the day — but even in the top band about 6 in 7 companies are not bought, and those lag. Buying the whole top list returned what the S&P 500 did (2012–2023), and adding "cheap" or "beaten-down" filters did not change that. Read it as context for a thesis you already have, never as the thesis.
Football field: where does the price sit?
Different valuation methods produce different fair-value ranges depending on assumptions. Plotting them together lets you see at a glance whether the current price is reasonable across approaches, or only one specific lens.
Industry multiples sourced from: broad market average (sector unknown). See the Peer Basket section below for the peer comparison and its limited-comparables caveat.
How does REG stack up against its closest peers?
We take the 8 same-industry companies most similar to REG (similar size) and check what investors are paying for each dollar of their revenue (or profits). If REG is much more expensive on the same yardstick, that's a red flag — unless you have a specific reason it deserves a premium. For a leveraged business, EV/EBIT and FCF yield (both in the table) are usually more reliable than EV/Sales, because revenue multiples ignore differences in margins and debt.
▾ What's "EV / Sales" in plain English?
EV (Enterprise Value) = market cap + total debt − cash. It's "what you'd pay to buy the entire company outright" — you pay the market cap to shareholders and take over their debt, but you keep their cash. EV is fairer than market cap alone because it includes the debt the new owner inherits.
EV / Sales = EV ÷ annual revenue. So "2.5×" means investors pay $2.50 of enterprise value per $1 of yearly sales. Higher = market is paying more per dollar of sales (usually because they expect future growth or fat margins).
p25 / median / p75 are the 25th, 50th (middle), and 75th percentile of the peers' multiples. Half the peers fall between p25 and p75. The median (p50) is the typical peer — that's the benchmark we compare to.
| EV / SalesEV / Sales — For every $1 of yearly revenue, this is how many dollars investors pay to own the whole business (including debt). Why it matters: Works for pre-profit growth companies where P/E and FCF don't apply. The most apples-to-apples cross-company multiple because it ignores accounting choices. Reference: 1–3x for mature companies · 4–10x for software/SaaS · 10–20x for hypergrowth · >20x is rare and demanding Full explanation → |
4.0x / 9.5x / 14.7x |
| EV / EBITEV / EBITDA — Enterprise value divided by earnings before interest, tax, depreciation, and amortization. Why it matters: A classic "what would a private buyer pay" multiple — used in M&A. Strips out tax and capital-structure noise. Reference: 8–12x for mature businesses · 15–25x for growth · Below 5x often signals distress Full explanation → |
14.0x / 14.9x / 31.3x |
Bold middle number = median peer. Half the peers trade above it, half below. Computed over 8 same-industry peers; implausible multiples excluded.
⚠️ Important caveat: peer multiples only work if the peers are genuinely comparable. Always check the peer list below — if the auto-picker grabbed micro-caps or unrelated businesses, the comparison is noise. A medical-device giant priced against tiny biotech startups won't produce a useful signal.
▾ View peer list (8)
| Ticker | Company | Industry | Mcap | EV/Sales | EV/GP | EV/EBIT | FCF Yield |
|---|---|---|---|---|---|---|---|
| SUI | SUN COMMUNITIES INC | REITs | $15.2B | 6.6x | — | — | 0.9% |
| WPC | W. P. Carey Inc. | REITs | $16.6B | 14.7x | — | — | 4.8% |
| RGLD | ROYAL GOLD INC | REITs | $19.1B | 19.4x | 27.9x | 31.3x | 0.8% |
| REXR | Rexford Industrial Realty, Inc. | REITs | $8.0B | 19,114.0x | — | — | 4.8% |
| RHP | Ryman Hospitality Properties, Inc. | REITs | $7.3B | 2.8x | — | 14.9x | 3.8% |
| STAG | STAG Industrial, Inc. | REITs | $7.2B | 12.4x | — | — | 4.0% |
| TFPM | Triple Flag Precious Metals Corp. | REITs | $6.5B | — | 24.9x | — | 3.0% |
| SSRM | SSR MINING INC. | REITs | $6.5B | 4.0x | — | 14.0x | 3.0% |
Real-estate-specific metrics
REITs are valued on AFFO (Adjusted Funds from Operations) and dividend yield, not DCF. Reported depreciation isn't a real cash cost for real estate — properties typically hold or appreciate. The metrics below are the industry-standard yardsticks.
Note: Depreciation & Amortization line not available — using FCF/share as AFFO proxy. Directionally correct but understates true AFFO (true AFFO adds back D&A and subtracts only maintenance CapEx; FCF subtracts all CapEx).
Quality & solvency checks
Cheap stocks can be cheap for a reason. These screens warn when a low valuation comes paired with structural fragility.
Why it matters: Cheap-looking stocks (low P/E or P/B) often have low Z-scores because the market knows the company is dying. Z-score warns you before you fall into a value trap.
Reference: > 3.0 = safe zone · 1.81–3.0 = grey zone · < 1.81 = distress zone
Full explanation →
REITs deliberately carry high leverage backed by long-life real estate and pay out 90%+ of taxable income — both inputs that Altman Z flags as distress. See the REIT Valuation Lens above for P/AFFO, dividend yield and payout ratio.
Why it matters: High score = fundamentals improving. Low score = deteriorating. Especially powerful for filtering cheap stocks: cheap + high F-score historically outperforms; cheap + low F-score is often a value trap.
Reference: 7–9 = strong · 4–6 = mediocre · 0–3 = weak
Full explanation →
Piotroski F's checks (operating cash flow, gross-margin trend, current ratio, asset turnover) assume an industrial cost structure, so they misread asset-heavy or financial businesses like this one — a healthy REIT, utility, pipeline, BDC/fund or holding company can score low for reasons that aren't weakness. See the sector lens above for the metrics that actually matter.
What if you assume different inputs?
Here's where we land — and what happens if you change the assumptions. Drag the sliders to set your own Discount RateDiscount Rate — The annual return you demand for taking single-stock risk instead of buying a safe Treasury or index fund.
Why it matters: Higher discount rate = stricter valuation (a stock has to produce more cash to be worth holding). Lower = more generous.
Reference: 8–12% is standard · 9–10% matches S&P 500 historical return · Below 7% is illogical for single-stock risk
Full explanation → (the annual return you demand for single-stock risk) and terminal growth; the value updates live so you can see whether the stock looks cheaper or richer. The discount rate starts at 7.5%, the figure our model used for REG. Open Advanced to also change beta, growth and the rate path.
Note: the calculator opens at our published value of $74.58 — it is initialised to the same scenario-weighted result, so the two match exactly on load. The moment you move a slider, the value below becomes a single-path what-if at your assumptions (not the three-scenario weighting), which is why it can differ from the headline once you've touched it.
7.5% — beta-based (CAPM), from this stock's BetaBeta — How much the stock moves when the overall market moves. 1.0 = moves with the market; 1.5 = moves 50% more than the market.
Why it matters: Higher beta = more volatile = should demand higher discount rate. Low beta stocks (utilities, consumer staples) move less.
Reference: Most stocks 0.5–1.5 · Defensives ~0.3 · High-vol tech ~1.5–2.0
Full explanation → of 0.55. The safe Treasury rate plus a premium scaled by how much more (or less) volatile the stock is than the market.
9.0% — sector/quality tier. A simpler hurdle set by industry and business durability: lower for stable, wide-moat companies; higher for speculative or micro-caps.
The headline value and this calculator start at 7.5% — the beta-based rate. Drag the slider to the other rate to see the full range.
A full intrinsic value isn't shown for REG because it's valued with a dividend-discount model this quick calculator doesn't replicate — see our published value above and the sector lens for the right metrics.
—
⚙ Advanced — tinker with every input (beta, growth, rate path, margin → full intrinsic value)
REGENCY CENTERS CORP (REG) is fairly valued, trading at a +3.7% premium to the model's estimate. The market is paying for its consistent profitability and positive operating cash flow, despite rising long-term debt. The primary quantifiable risk is the continued increase in long-term debt, which has risen from $3719M to $4739M.
As of 3 months ago
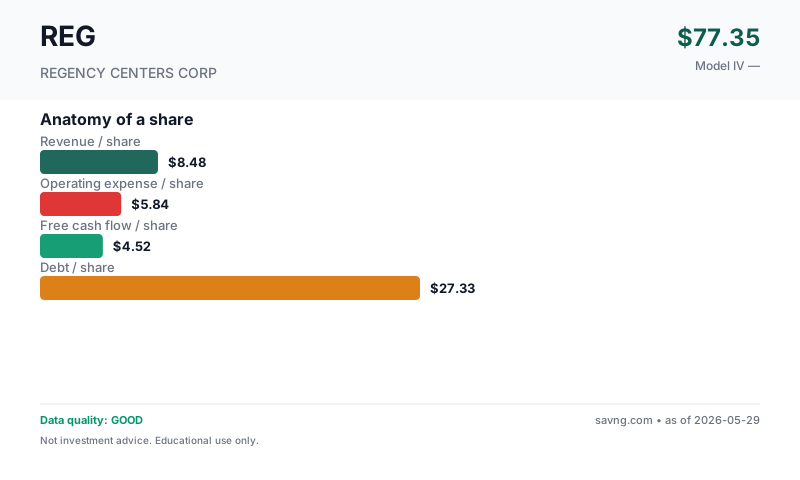
Anatomy of a share
What you're buying per share. Bars are at the same scale so you can see the relative size of revenue, costs, cash flow, and debt — not just read them in a table.
What's free cash flow / what do these mean?
Revenue per share — how much the business earns from customers, divided by the number of shares outstanding. Top of the income statement.
Earnings per share — profit left after operating costs, interest, and taxes, per share. Two versions appear on this page and are not interchangeable: GAAP diluted EPS uses the company's weighted-average diluted share count during the reporting period (this is the "earnings" in "price-to-earnings"); net income per current share divides annual net income by today's share count. They differ whenever the share count has changed.
Owner-earnings free cash flow per share — the cash the business produces for shareholders. Savng's owner-earnings FCF subtracts capital expenditures and stock-based compensation from operating cash flow (SBC is a real dilution cost even though it's non-cash). This is deliberately more conservative than "standard" FCF, which subtracts only capital expenditures — so our figure is lower than the headline FCF you'll see elsewhere. FCF funds dividends, buybacks, debt repayment, and acquisitions; a company can report positive earnings yet negative FCF.
Debt per share — total interest-bearing borrowings divided by shares. High debt-per-share next to thin FCF-per-share is a fragility signal.
What you actually need to decide
Every stock price is a disagreement. Here's the single thing that must go right for the bulls, the single thing that breaks the thesis, and the concrete signposts to watch so you can update your view as real results arrive.
- Next quarter's revenue growth rate
- Changes in long-term debt levels
- Operating cash flow trends
The trend, in plain numbers (FY2024 → FY2025, latest reported)
Straight from the financial statements — no model, no opinion. For a small or unprofitable company, the direction of these numbers usually tells you more than any single valuation.
- Revenue grew +7% to $1.55B.
- Free cash flow rose to $808.2M.
- Net income grew +32% to $527.5M.
Nothing was clearly worsening year-over-year.
Management & Leadership
Lisa Palmer serves as the President and Chief Executive Officer of Regency Centers, having been with the company for over two decades and in her current role since 2020. She leads the company's strategic direction and operations in the retail real estate sector. Michael Mas is the Executive Vice President and Chief Financial Officer.
What They Make
Regency Centers is a real estate investment trust (REITREIT (Real Estate Investment Trust) — A company that owns income-producing real estate and is required to pay out about 90% of its profit to shareholders as dividends.
Why it matters: Because they pay out almost everything, REITs are judged on the cash they distribute (price-to-AFFO and dividend yield), not on ordinary earnings — a normal P/E or DCF misleads here.
Reference: Dividend yields often 3–6%; valued on price-to-AFFO, not P/E.
Full explanation →) that owns, operates, and develops grocery-anchored shopping centers. Its properties primarily serve everyday needs for local communities.
End Markets
Revenue Drivers
Why Is It Priced Like This?
Why Customers Pay
The market prices REG at a +3.7% premium, reflecting its consistent profitability, with net income positive for 5/5 years, and positive operating cash flow for 5/5 years. Investors are likely valuing the stability and income generation from its grocery-anchored portfolio, despite the rising long-term debt from $3719M to $4739M.
Three Scenarios, Weighted
| Scenario | IV | Upside from today's price | Weight |
|---|---|---|---|
| Conservative | $63.53 | -12.9% | 40% |
| Base | $75.89 | 4.0% | 35% |
| Optimistic | $90.44 | 24.0% | 25% |
| Weighted | $74.58 | 2.2% | 100% |
Reading the last column: it is the move from today's price to each value (IV ÷ price − 1). The headline "premium/discount to model IV" measures the same gap from the value's side (price ÷ IV − 1), so the two percentages differ in size and sign by construction — e.g. a price 8% above value is a value 7.4% below price.
Business Model & Valuation
How They Make Money
The company pays an estimated dividend of $2.79/yr, derived from its cash-flow statement, indicating a focus on returning capital to shareholders.
Dividend Discount Medium
REIT (REITs): dividend discount model - GAAP earnings distort REIT valuations.
Show advanced inputs
What this model does NOT do: this is a consolidated owner-earnings FCF model. Standalone segment assumptions: none. It does not project net interest income and fee-income lines independently; their combined effect is embedded in the historical revenue and cash-flow trend the model extrapolates. The calculator above can only approximate a segment's impact through the single consolidated growth rate — it cannot model any one line separately. For a true segment-level view, build a separate model from the company's segment disclosures.
Maturity & Competitive Position
Moat Signals
Revenue is growing at 7.4%/yr over 4 years, from $1166M to $1554M.
Geography & Markets
Regency Centers operates primarily in the United States, focusing on affluent and densely populated areas. Exact geographic segment percentages are not available from current data sources.
Geographic Risks
Market Signals
These are timing signals, not value signals — they describe the stock's recent price behavior, not what the business is worth. Use them for the "the thesis looks good, but is now the moment?" question. Each tile below explains what it's saying.
Why it matters: Short-term contrarian indicator. Extreme readings often precede mean reversion, though not always.
Reference: 30–70 normal · >70 overbought · <30 oversold
Full explanation → (14)44.5NeutralMomentum is balanced — neither overbought nor oversold.
Why it matters: When the fast line crosses above the slow line, short-term momentum is turning up; below, turning down. A timing cue, not a value signal.
Reference: Line above signal = bullish momentum · below = bearish
Full explanation →BullishLine above signalThe fast trend is above the slow trend — short-term momentum is currently upward.
Technicals describe price, not the business. A great company can have a "bearish" tape (a buying chance) and a weak one a "bullish" tape (a trap). Pair these with the valuation and health sections above.
QUALITY
Data Quality & Risk Flags (2 notes — click to expand/collapse)
Guardrail Notes (2)
- Dividend derived from cash-flow statement ($2.79/yr; SEC has no per-share dividend feed).
- Dividend data sparse; DDM using estimated yield. Confidence reduced.
FINANCIALS
Financial Statements (5-year tables — click to expand)
From REGENCY CENTERS CORP's SEC filings (EDGAR).
Income (5yr)
| Year | Revenue | Net Income | EPS |
|---|---|---|---|
| 2025 | 1.6B | 527.5M | $2.88 |
| 2024 | 1.5B | 400.4M | $2.19 |
| 2023 | 1.3B | 364.6M | $1.99 |
| 2022 | 1.2B | 482.9M | $2.64 |
| 2021 | 1.2B | 361.4M | $1.97 |
Cash Flow (5yr)
Capital expenditure isn't tagged in this filer's machine-readable data (the CapEx column shows "—"). The free-cash-flow column is therefore operating cash flow less stock-based compensation only — an upper bound on true owner earnings, not the real figure. Companies that report capex under a custom label (some large IFRS filers do) look better here than they are.
| Year | Operating CF | CapEx | − SBC & adj. | Free Cash Flow |
|---|---|---|---|---|
| 2025 | 827.7M | — | 19.5M | 808.2M |
| 2024 | 790.2M | — | 23.5M | 766.7M |
| 2023 | 719.6M | — | 20.1M | 699.5M |
| 2022 | 655.8M | — | 16.5M | 639.3M |
| 2021 | 659.4M | — | 12.5M | 646.9M |
How we define FCF: operating cash flow − capital expenditure − stock-based compensation (owner-earnings basis — SBC is a real cost to shareholders even though it's non-cash). Latest year: 827.7M − — − 19.5M (SBC & adj.) = 808.2M. This is the same owner-earnings FCF definition the valuation model uses, though the DCF's starting value is a TTM dividend, not this single year.
Balance Sheet
| Total Assets | 13.0B |
| Total Liabilities | 5.8B |
| Equity | 6.9B |
| Total Debt | 4.7B |
Similar companies worth a look
Same sector and industry, similar fundamentals shape. Verify everything yourself — this list is computed mechanically and does not reflect our judgment about whether any of these are a good investment.